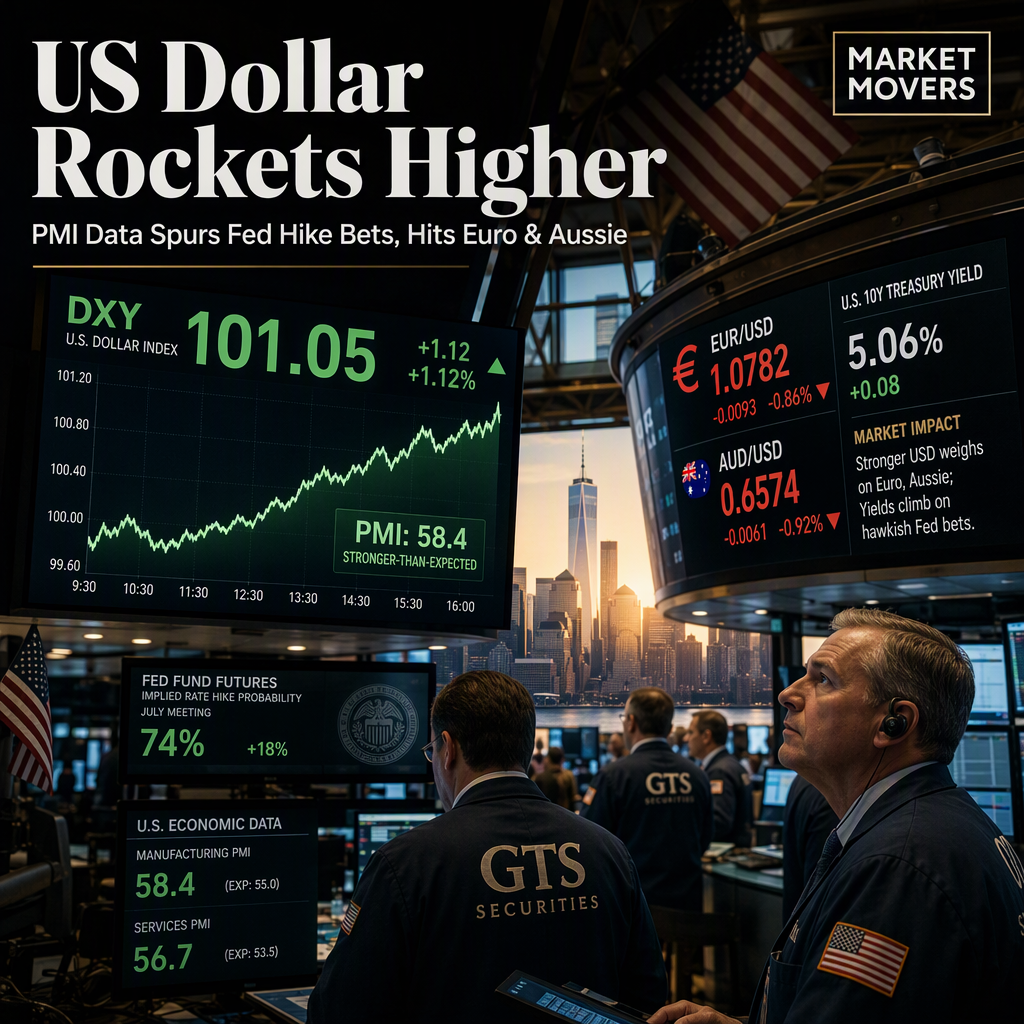
Stronger-than-expected US business activity data released on Wednesday drove significant moves in global currency markets, with both the Euro and Australian Dollar falling sharply against the US Dollar [1][2]. The preliminary S&P Global US Composite Purchasing Managers’ Index (PMI) rose to 58.4 in September from 56.0 in August, marking a notable acceleration in private-sector activity. The Manufacturing PMI climbed to 57.0, beating the 53.5 forecast, while the Services PMI rose to 58.7, surpassing expectations of 56.0 [1][2]. Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, stated that US business activity is expanding at its fastest pace in more than five years [2].
The robust US data reinforced expectations of further Federal Reserve (Fed) tightening. The US Dollar Index (DXY) gained 0.53% to trade around 101.05, reaching its highest level since July 31 and a fresh two-month high [1][2]. Traders now see a 68% chance of another Fed rate hike at the October meeting, up from 53% before the PMI release according to the CME FedWatch Tool [1][2]. The Fed had already raised rates by 25 basis points last week, bringing the target range to 3.75%-4%, and its latest projections indicate at least one more hike this year [2]. Fed Governor Michael Barr commented that US growth is strong, the labor market is solid, and inflation is not clearly moving back towards the 2% target, suggesting more rate hikes may be needed [1]. US Treasury yields also remain elevated, with the ten-year yield hovering around 5.06% [2].
The Euro and Australian Dollar both suffered in response to the US data. EUR/USD extended its decline, trading around 1.1401, near levels last seen in late July [1]. AUD/USD tumbled 1.07% to around 0.7040, pressured further by disappointing Australian PMI data. Australia's Composite PMI fell to 50.8 from 52.7 in August, with contractions in manufacturing and a slowdown in services, tempering expectations for Reserve Bank of Australia (RBA) tightening [2]. Despite this, the RBA is still expected to raise its policy rate by 25 basis points next week [2].
Eurozone PMI data also beat forecasts and remained in expansion territory, supporting the case for another European Central Bank (ECB) rate hike. ECB policymaker Joachim Nagel stated that rates are still in neutral territory and a move into 'mild restrictive territory' cannot be ruled out, citing persistent core inflation [1].
Geopolitical developments in the Middle East were also noted, with a senior Iranian official stating that reopening the Strait of Hormuz and lifting the US blockade were discussed during indirect talks with the US, and Tehran is reviewing Washington’s response to its proposal to end hostilities [1].
CONCLUSION
Stronger US PMI data has fueled expectations of further Fed rate hikes, boosting the US Dollar to multi-month highs and putting significant pressure on both the Euro and Australian Dollar. Market participants are now pricing in a higher probability of an October Fed hike, while elevated Treasury yields add further support to the Greenback. The combination of robust US economic momentum and central bank divergence is driving notable currency market volatility.