
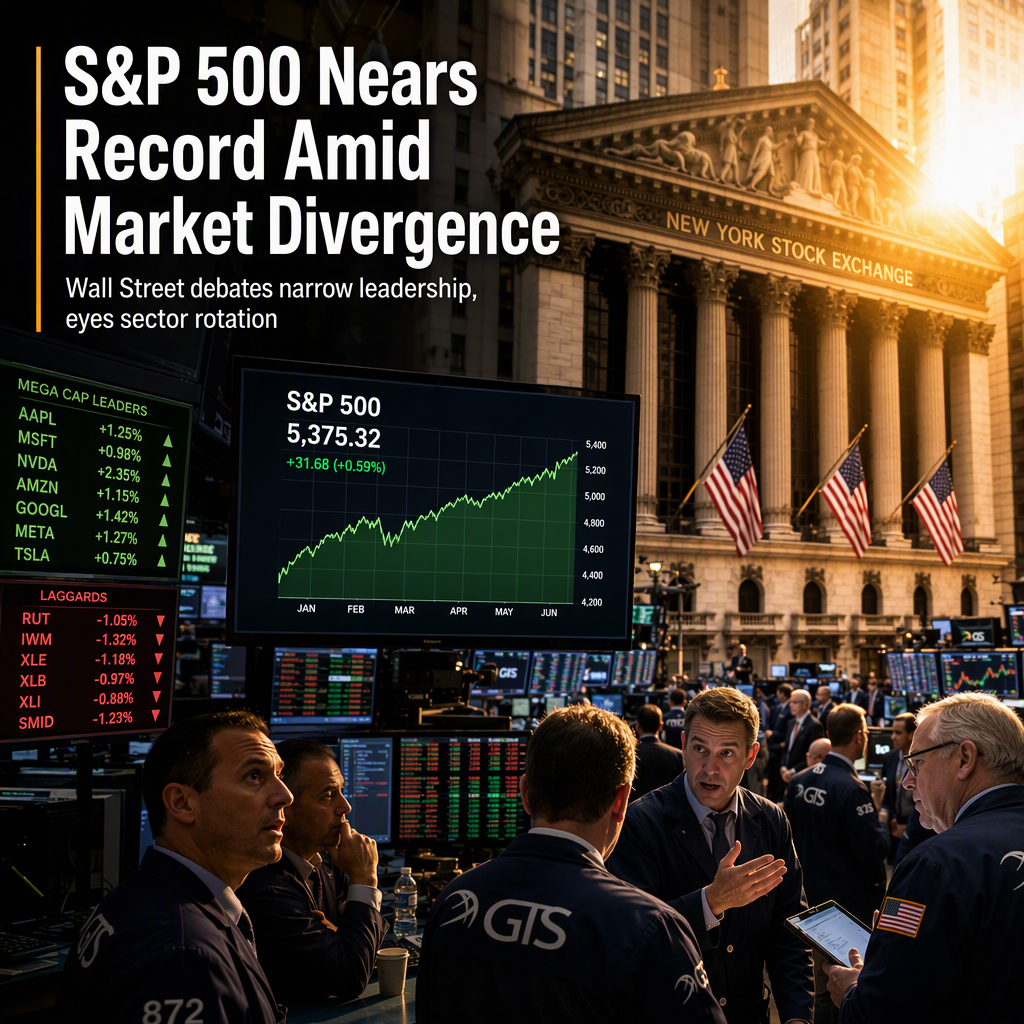
The U.S. stock market is currently at a critical juncture, with the S&P 500 index hovering just below a record high while the median stock in the index remains in a 16% drawdown, highlighting a significant divergence in performance across equities [1]. This split has become a central topic among Wall Street professionals, many of whom believe the situation will ultimately resolve in favor of bullish investors [1].
Goldman Sachs' co-head of equity-derivatives sales, Lee Coppersmith, noted that market breadth has deteriorated to its weakest level since the DotCom Bubble, with the headline index masking underlying difficulties. Despite this, Coppersmith expressed a positive outlook, stating, 'I'm increasingly of the view that it isn't [a warning sign], and continue to favor SPX higher over the next 1-3 months' [1].
Morgan Stanley equity strategist Mike Wilson observed that rising Treasury yields have impacted average stocks more than mega-cap leaders, but he believes the risk has already been priced into most stocks ahead of earnings season. Wilson suggested that if yields stabilize and earnings revisions hold, there is potential for a catch-up in performance among lagging stocks [1].
Deutsche Bank strategists downgraded the tech sector on Monday, citing crowded investor positioning, high expectations for earnings, and the sector's recent outperformance in driving the S&P 500. However, they also predicted that a reset in tech could allow other sectors and small caps to rise, potentially alleviating concerns about market breadth [1].
Overall, the market's narrow leadership has made it difficult for investors to outperform the S&P 500, but several analysts see opportunities for broader participation if sector rotation occurs [1].
CONCLUSION
The market is experiencing a pronounced divergence, with mega-cap stocks driving the S&P 500 near record highs while most stocks lag. Despite concerns about narrow leadership, several analysts anticipate a potential broadening of market gains if yields stabilize and sector rotation materializes. The consensus leans cautiously optimistic for the near term.