
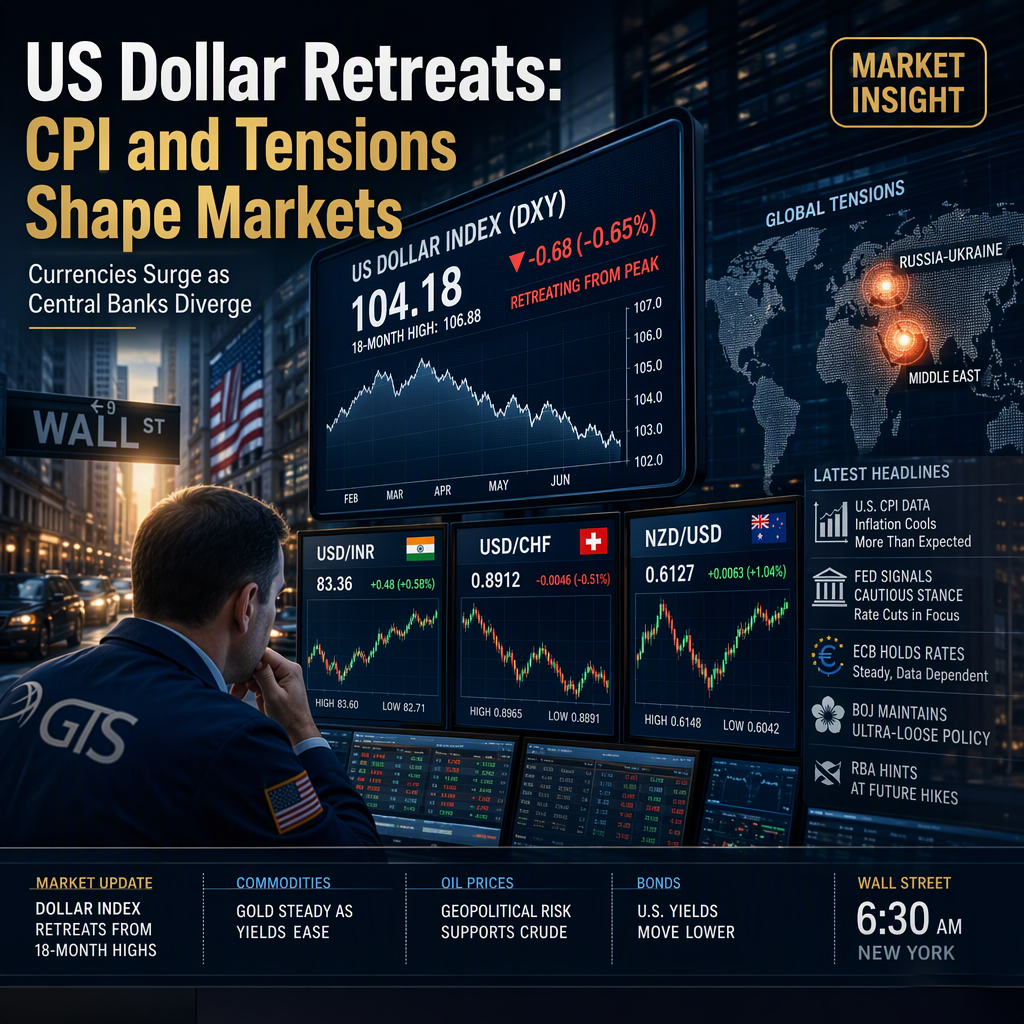
The US Dollar Index (DXY) pulled back to around 102.40 after briefly touching an 18-month high of 102.61, as investors shifted focus to the upcoming US Consumer Price Index (CPI) data for September, which is expected to significantly influence the Federal Reserve's rate path [2][3]. The Dollar's retreat contributed to gains in other currencies, with the Indian Rupee (INR) extending its advance against the US Dollar (USD), and the USD/INR pair tumbling 0.6% to near 95.00, its lowest level in over a month [1]. This move was driven by the Reserve Bank of India's (RBI) announcement of a broad package of measures to support the INR, including a special dollar window for three state-run oil companies, a halt to the re-booking of cancelled FX derivative contracts involving the rupee, and the introduction of an FX risk reserve requirement on transactions exceeding $2 million [1].
In parallel, the Swiss Franc (CHF) strengthened as USD/CHF declined to around 0.8330, with the Swiss National Bank (SNB) maintaining a dovish stance by keeping its key interest rate at 0% during its September meeting [2]. SNB Vice Chairman Antoine Martin stated that no rate adjustments are currently required, citing low, stable inflation and minimal spillover risks [2]. UOB Group strategists expect USD/CHF to remain in a range-trading phase between 0.8245 and 0.8365 in the coming weeks [2].
The New Zealand Dollar (NZD) also rebounded to near 0.5600, though it remains close to an 18-month low amid ongoing Middle East tensions and higher oil prices [3]. Geopolitical risks, including a deadly strike on Riyadh's King Khalid International Airport and renewed drone and missile attacks from Yemen's Iran-backed Houthis, have heightened safe-haven demand for the US Dollar [2][3]. Additionally, uncertainty persists due to the ongoing Russia-Ukraine conflict and concerns over global energy supply [2][3].
Market participants are closely watching Wednesday's US CPI report, with consensus estimates pointing to a headline inflation rate of 3.7% year-on-year for September, up from 3.4% in August, and a core CPI of 2.5% year-on-year, higher than the previous 2.4% [1]. According to the CME FedWatch Tool, there is roughly an 80% likelihood that the Federal Reserve will leave interest rates unchanged at its upcoming meeting, but an 88% chance of a rate hike in December [2][3]. Several Fed officials have pushed back against a back-to-back hike at the October 28 FOMC meeting, potentially limiting the USD’s upside [3]. However, Fed’s Hammack delivered a notably more hawkish tone, emphasizing the need for higher interest rates and warning of persistent inflation risks [1][3].
In India, retail CPI for September rose to 5.54% year-on-year, exceeding estimates and the previous reading, with economists noting that inflation has remained above the RBI’s 4% target for four consecutive months [1]. Societe Generale analysts suggest that the recent upturn in inflation is broad-based and may mark the beginning of a new tightening cycle by the RBI [1].
CONCLUSION
The US Dollar's recent pullback from 18-month highs reflects heightened market caution ahead of key US CPI data and amid escalating geopolitical tensions. Central banks in India and Switzerland are taking divergent policy actions, with the RBI tightening measures to support the rupee and the SNB maintaining a dovish stance. Market sentiment remains cautious, with expectations for a Fed pause in October but a possible rate hike in December hinging on upcoming inflation data.