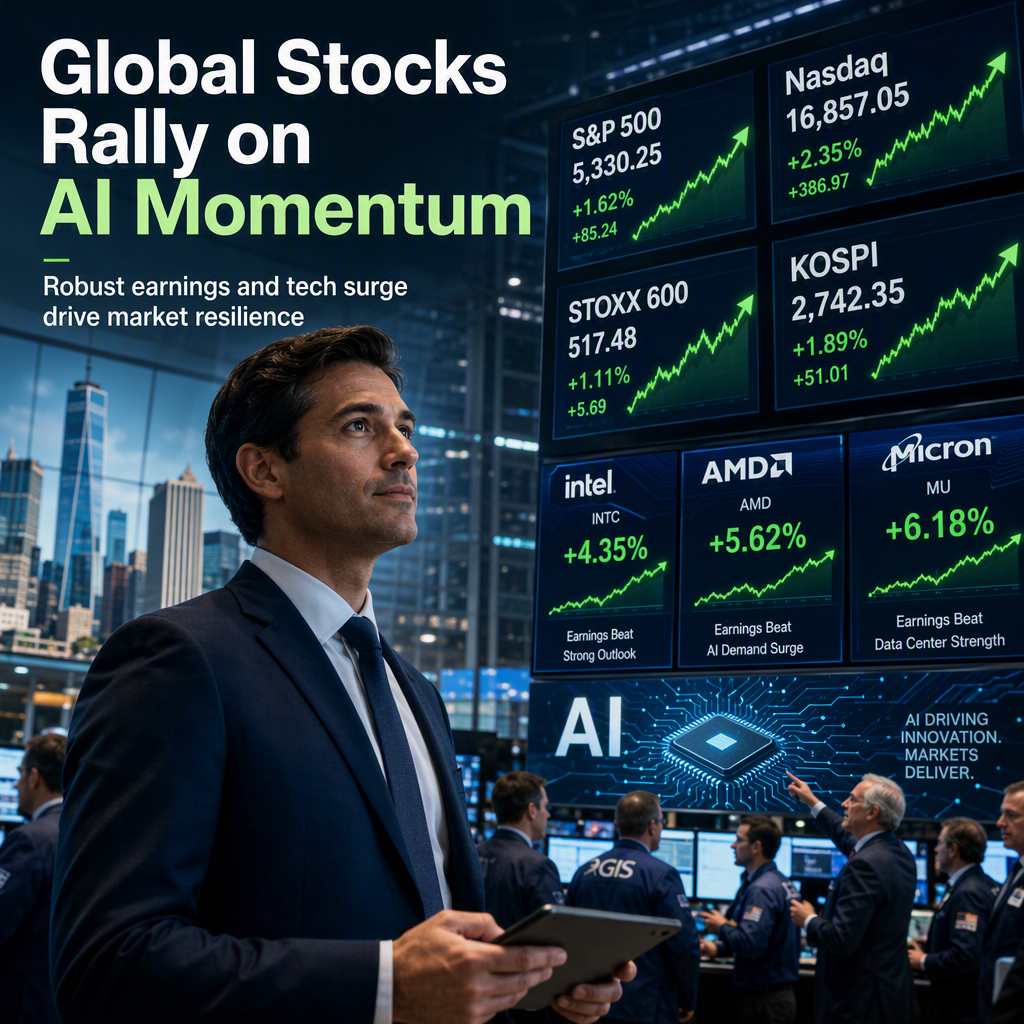
According to Danske Bank's Danske Research Team, global equities experienced a strong rebound, with major indices posting solid gains despite a recent Federal Reserve hike and the pricing in of four additional hikes over the next 12 months [1]. The S&P 500 advanced by 1.2%, the Nasdaq gained 1.7%—marking its best session since early August—while the Stoxx 600 rose 0.9%, and the Kospi surged 2.7% at the time of reporting [1].
The research team attributes this resilience to robust consensus earnings growth of 35% for the year, with estimates continuing to trend upward. This earnings momentum is making a sustained equity sell-off or even a pause increasingly difficult, as compounding earnings and contracting valuation multiples provide a cushion against higher rates [1].
The standout driver of the rally was the AI trade, with semiconductor and memory stocks leading the advance. Notably, Intel, AMD, and Micron rallied between 6-8% [1]. Big tech also posted solid gains, reinforcing the sector's leadership in the current market environment. In contrast, industrials were among the weakest performers despite the broader risk-on backdrop, suggesting that investors are becoming more selective and favoring sectors with stronger earnings growth and more attractive valuations [1].
Danske Bank advocates a barbell strategy, recommending overweight positions in global tech stocks with historical earnings growth and undemanding valuations, financed by underweight positions in global industrials, where valuations remain elevated despite significantly weaker earnings [1].
CONCLUSION
Global equities have rebounded strongly, driven by robust earnings growth and an AI-led rally in tech and semiconductor stocks. Despite recent Fed tightening, the market remains resilient, with investors increasingly favoring tech over industrials. The outlook is positive, supported by rising earnings estimates and selective sector positioning.