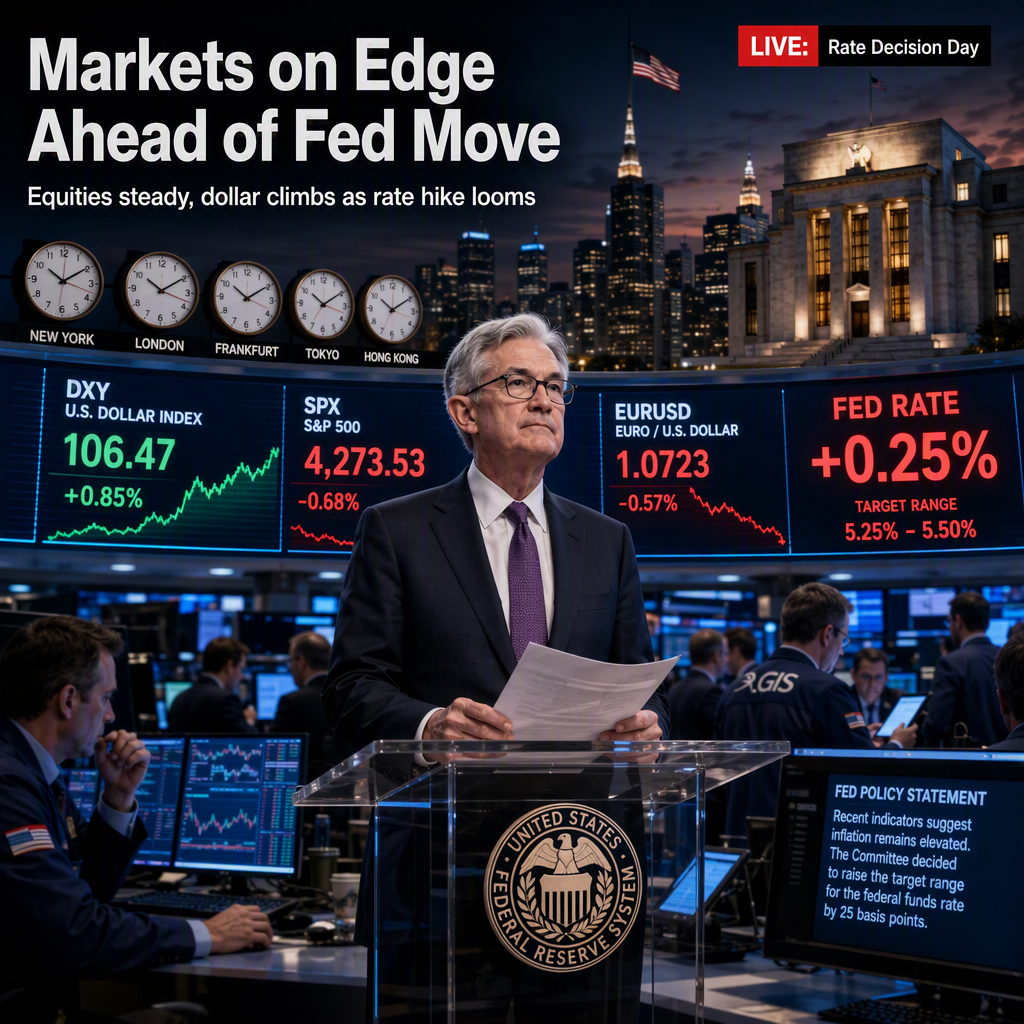
Global financial markets are focused on the US Federal Reserve's upcoming interest rate decision, with widespread expectations of a 25 basis point hike that would bring the benchmark rate to a range of 3.75% to 4.00% [3][7]. Market participants are pricing in a probability of over 90% for this move, with the CME FedWatch tool indicating a 92.5% chance and Deutsche Bank strategists citing a 94% probability [4][7]. The decision is anticipated to be accompanied by guidance from Chair Warsh and an updated dot plot, which are expected to shape market sentiment moving forward [4].
Ahead of the announcement, the US Dollar has strengthened, supported by elevated US bond yields and safe-haven demand amid rising oil prices and geopolitical tensions in the Middle East [1][4]. The GBP/USD pair has retreated to the 1.3470-1.3465 region, near a one-month low, as traders await the Fed's decision, with technical analysis suggesting further downside risk if the pair breaks below the 200-day SMA at 1.3455 [1]. Similarly, USD/JPY is trading cautiously around 155.00, with analysts at BNY expecting the Fed to hike rates and possibly signal one more increase this year, though they caution that the path to significantly tighter policy faces obstacles [3].
Equity markets have experienced volatility, with the S&P 500 falling to a six-week low (-0.45%) and the STOXX 600 dropping to a three-month low (-0.28%) on Tuesday, driven by stagflation fears and higher energy prices [4][7]. However, a pullback in oil prices has helped stabilize Asian markets and US equity futures, with S&P 500 futures up 0.22% and Dow Jones futures rising 0.14% ahead of the Fed decision [4][7]. The 10-year US Treasury yield briefly reached a post-2007 high of 5.04% before settling at 5.00%, reflecting persistent pressure on bonds as markets adjust to a higher-for-longer Fed policy [7].
In the currency space, ING analysts suggest the Fed announcement could push EUR/USD towards 1.150, with risks becoming more balanced below that level due to technicals and rate differentials [2]. They also note that both the Fed and ECB are expected to remain on hold in the near term, which could lead to dovish repricing in both EUR and USD curves [2]. Meanwhile, the EUR/GBP is trading slightly higher after UK inflation data met expectations, and the Bank of England is expected to deliver a more dovish message relative to market expectations [2].
Analyst opinions are mixed on the forward path for rates. While BNY expects the Fed to hike and possibly signal one more increase this year, they caution that the market may be ahead of itself in pricing nearly 100 basis points of additional hikes [3]. ING and Deutsche Bank both emphasize the importance of the Fed's guidance and the potential for dovish repricing if both the Fed and ECB pause further hikes [2][4].
CONCLUSION
Markets are firmly positioned for a 25 basis point Fed rate hike, with attention turning to the central bank's guidance for future policy. Equities have stabilized after recent declines, while the US Dollar remains strong and bond yields elevated. The Fed's tone and projections will be critical in shaping the next phase of market direction.