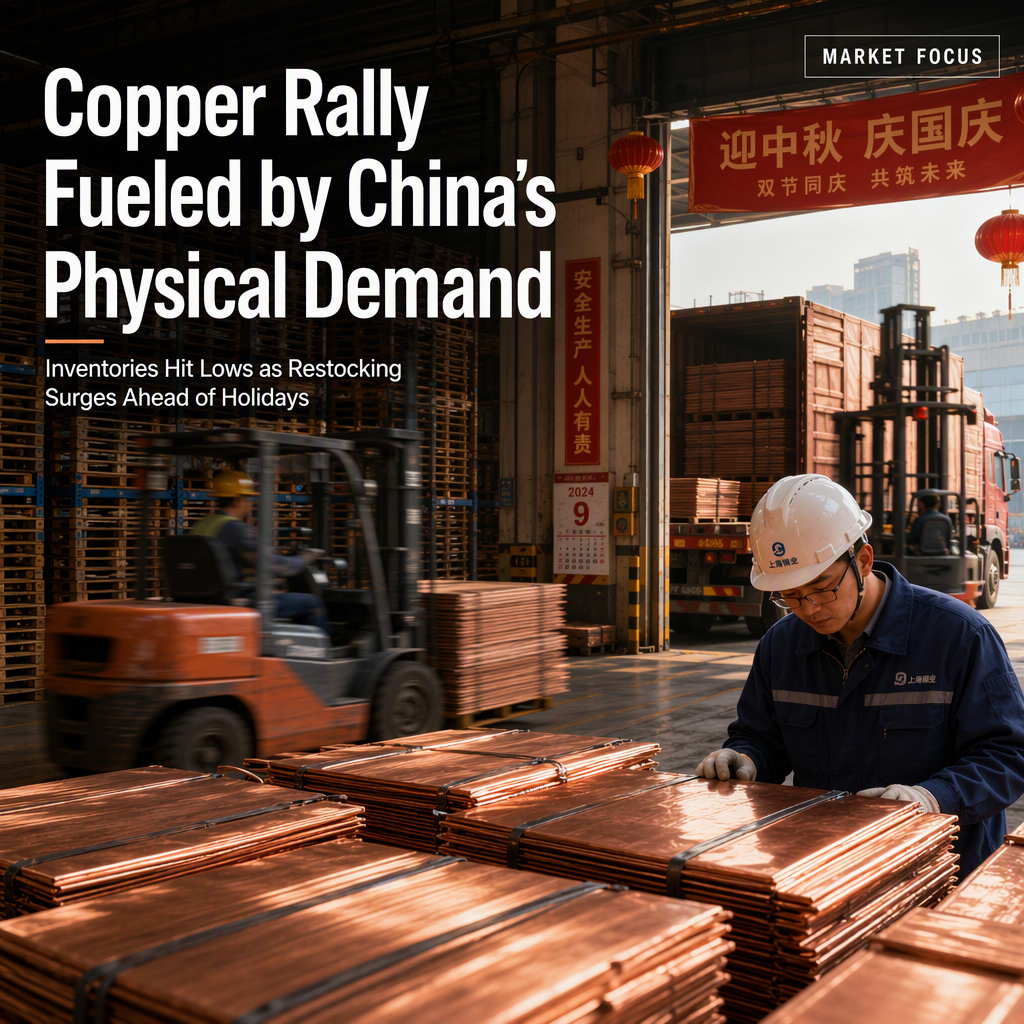
LME copper prices have extended gains for a sixth consecutive session, marking the longest winning streak since May, before experiencing a slight retreat on Wednesday morning. This rally has been primarily supported by tight physical market conditions in China, including falling inventories and increased restocking activity ahead of the Mid-Autumn Festival and National Day holidays, which have boosted consumption. Specifically, Shanghai copper cathode inventories dropped by 14,700 tonnes to 43,900 tonnes, reaching their lowest level since December 2023. Although imported copper arrivals have increased, most of the material has been directed straight to fabricators rather than warehouses, maintaining tight spot supplies [1].
Despite the upward movement in copper prices, investor positioning across base metals has remained subdued. The latest COTR data shows that net bullish copper futures positions declined by 3,981 lots to 42,132 lots, the lowest since late March and marking a sixth consecutive weekly decline. This trend of reduced investor interest is also evident in other base metals: aluminium net longs fell by 11,623 lots to 77,423 lots, mainly due to long liquidation, while zinc net longs dropped by 2,787 lots to 29,946 lots, extending their decline for a fourth straight week [1].
The contrast between strong physical demand in China and weak investor positioning highlights a divergence in market sentiment. ING analysts Ewa Manthey and Warren Patterson note that while physical tightness is supporting prices, investor participation remains soft, suggesting that the current rally is driven more by supply-demand fundamentals in China than by speculative activity [1].
CONCLUSION
Copper prices are being supported by tight physical conditions and falling inventories in China, even as investor positioning remains weak. The market's current strength appears rooted in robust Chinese demand and supply constraints rather than speculative interest, indicating a rally driven by fundamentals.