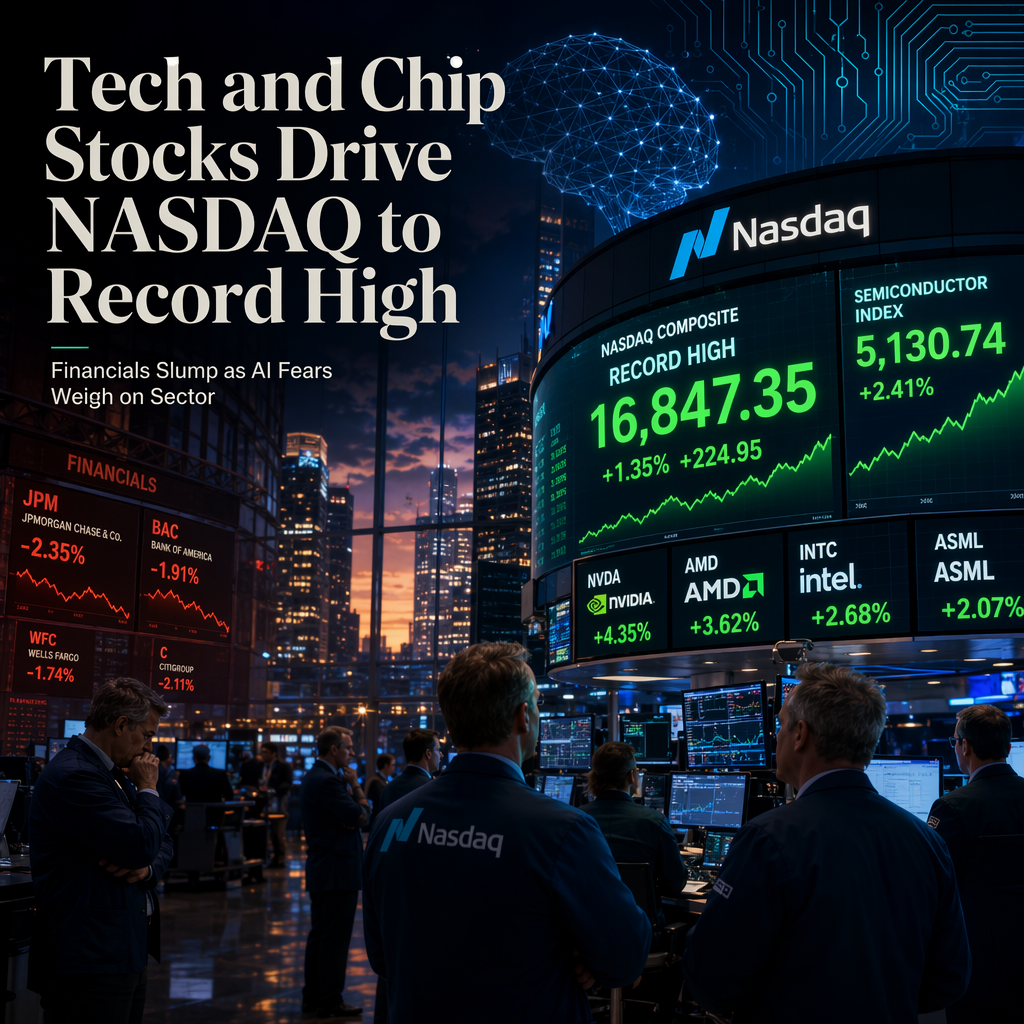
United States equities closed virtually flat, with the S&P 500 declining by just -0.001%, as gains in technology and semiconductor stocks offset a sharp drop in financial shares [1]. The NASDAQ outperformed, rising +0.45% to reach a new all-time high, driven by continued strength in chip stocks. The Philadelphia Semiconductor Index advanced +2.06%, marking its sixth consecutive gain [1]. In contrast, financials led the declines within the S&P 500, falling -1.98%, amid concerns that artificial intelligence (AI) could erode margins and fees in the sector [1].
During the same period, former President Trump addressed AI in a speech at the UN, describing it as 'super intelligence' and rejecting efforts to control its development [1]. European equities posted modest gains, with the Stoxx 600 up +0.13%, the CAC 40 rising +0.20%, and the DAX edging higher by +0.02%. The UK’s FTSE 100 was an exception, dropping -0.29% [1].
Asian markets showed mixed performance: South Korea’s KOSPI gained +0.45%, while Chinese equities were under pressure, with the Hang Seng down -0.74%, the CSI 300 off -0.50%, and the Shanghai Composite lower by -0.36%. Australia’s S&P/ASX 200 was little changed, up +0.08%. US equity futures remained near flat, with S&P 500 futures up +0.09% [1].
The market's sector rotation highlights ongoing investor enthusiasm for technology and semiconductor stocks, even as concerns about AI's impact on financial sector profitability weigh on sentiment [1].
CONCLUSION
The market closed flat overall, with technology and semiconductor stocks driving gains that offset losses in financials. Persistent concerns about AI's effect on financial sector margins contributed to the sector's underperformance. The NASDAQ's record high underscores continued investor confidence in tech, while broader market sentiment remains cautious.