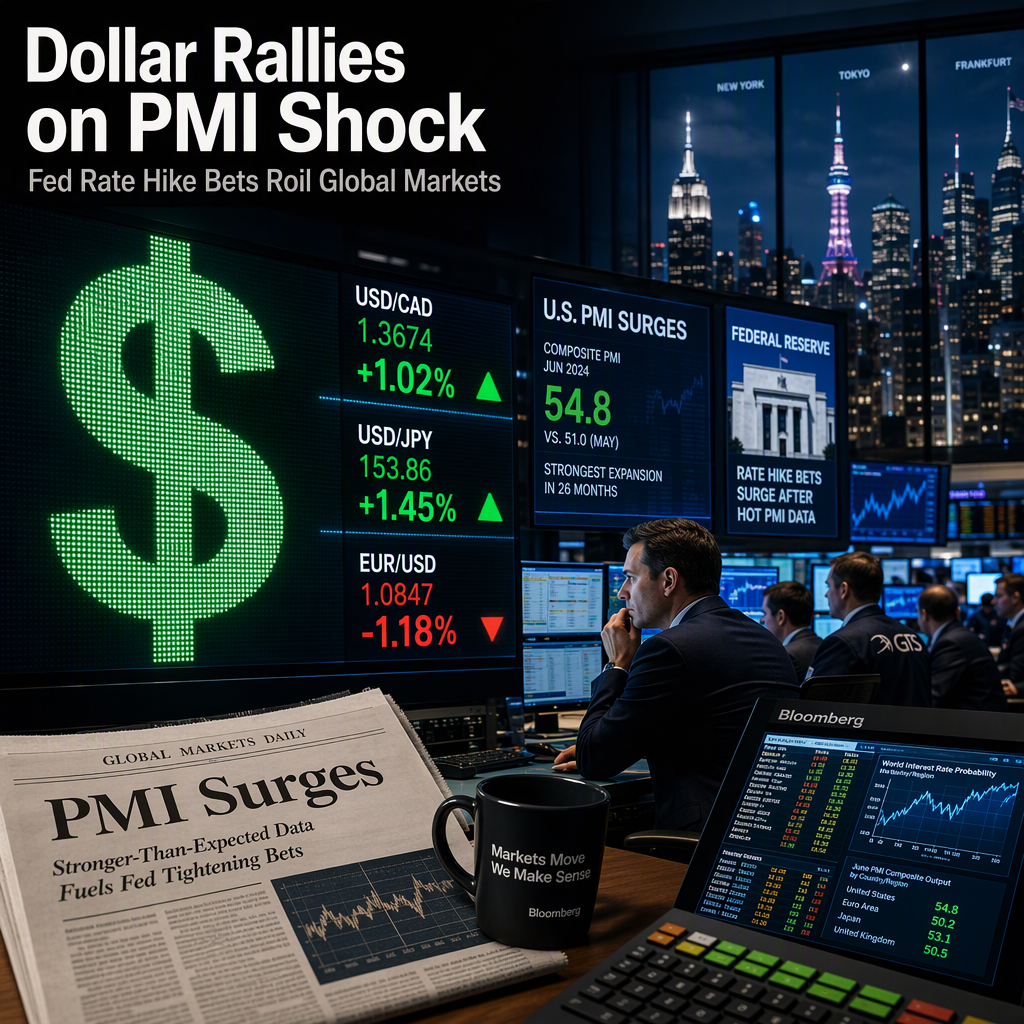
The US Dollar (USD) strengthened significantly against major currencies, including the Canadian Dollar (CAD), Japanese Yen (JPY), and Euro (EUR), following the release of robust US S&P Global flash Purchasing Managers Index (PMI) data on Wednesday. The US Composite PMI climbed to 58.4 in September from 56.0 in August, while Manufacturing PMI rose to 57.0 from 53.9, and Services PMI improved to 58.7 from 56.5, all surpassing market expectations and consensus forecasts [1][3]. These figures marked the fastest pace of US business activity in five years, with firms reporting strong job growth and rising wages amid elevated input costs [2][3].
The strong PMI data reignited inflation fears and reinforced expectations for further US Federal Reserve (Fed) rate hikes. Markets are now pricing in roughly a 69.7% to 70% probability of a quarter-point Fed rate hike in October, up from 48.7% a week ago, according to the CME FedWatch tool and Danske Bank [1][3]. Federal Reserve Governor Michael Barr emphasized the importance of price stability for durable growth and maximum employment, delivering a notably hawkish message that supported the Dollar's upside [1][2].
The USD/CAD pair traded near 1.4100, holding a bullish bias above the 100-day SMA, while USD/JPY consolidated gains at 158.30, testing the key 200-day SMA resistance. USD/JPY appreciated 0.8% this week and rallied more than 3% in less than two weeks, with technical indicators supporting further bullish momentum [1][2]. The EUR/USD pair dropped below 1.14 as markets reacted to the US data, with Danske Bank highlighting rising services input prices and tighter financial conditions as key drivers of Dollar strength [3].
Market reactions included a sharp tightening in financial conditions, with both equity and bond markets selling off and the USD strengthening across all G10 currencies [3]. The US Dollar was the strongest against the Australian Dollar this week, with percentage gains also noted against EUR, GBP, JPY, and CAD [2]. Meanwhile, crude oil prices fell amid hopes for diplomatic progress between the US and Iran, negatively impacting the CAD due to Canada's status as a major oil exporter [1].
Forward-looking statements from strategists and analysts suggest continued vigilance regarding inflation and currency-driven price pressures. Scotiabank noted that the Bank of Canada (BoC) remains open to tighter policy but has not signaled a decisive shift ahead of its October meeting, while Danske Bank expects two further ECB hikes, with energy prices determining the timing [1][3].
CONCLUSION
Robust US PMI data has triggered a broad rally in the US Dollar, reinforcing expectations for further Fed rate hikes and tightening financial conditions across global markets. The USD's strength has pressured major currencies, with notable declines in EUR/USD, USD/CAD, and USD/JPY. Analysts and strategists remain focused on inflation risks and upcoming central bank decisions, suggesting continued volatility in FX and bond markets.