
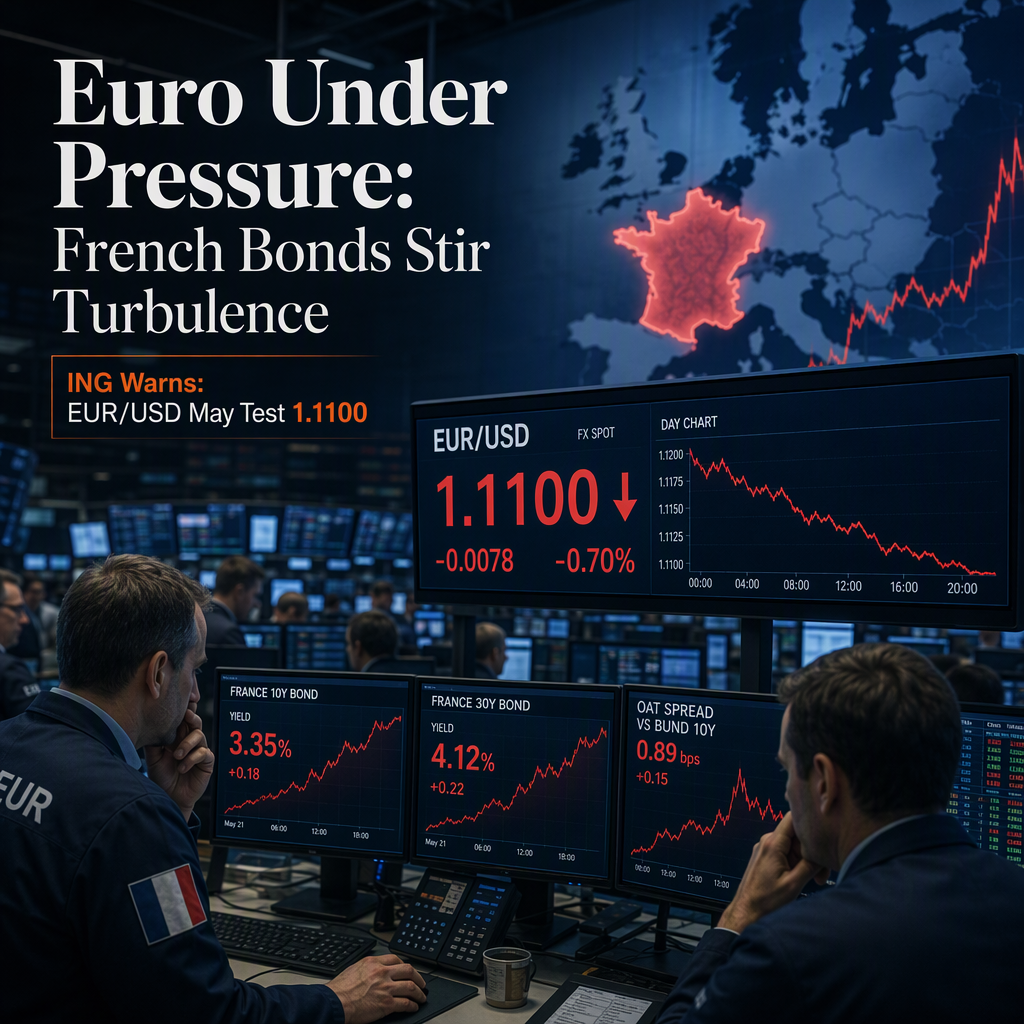
The Euro (EUR) is experiencing significant downside pressure due to ongoing turbulence in the French bond market, according to Francesco Pesole at ING. This turbulence has introduced a fiscal risk premium to the Euro, which, while not yet extreme, is contributing to a repricing lower in European Central Bank (ECB) rate expectations [1]. The repricing is evident in the decline in market pricing for the March ECB meeting, which has dropped from 80 basis points on 24 September to 45 basis points currently. This movement is described as a very EUR-specific development and has pushed the EUR:USD two-year swap rate differential (ESTR-SOFR) to -167 basis points, a level last seen in August 2025 [1].
The Euro began the week at the bottom of the G10 scorecard, highlighting the impact of French fiscal concerns on FX investor sentiment. The Euro is being affected both directly, through the addition of a fiscal risk premium, and indirectly, via the repricing of ECB rate expectations [1]. Some relief in French bonds was observed yesterday, which allowed EUR/USD to recover slightly to just above 1.1200 after previously falling to 1.1160. However, ING expresses limited confidence in a sustained rebound, warning that the fiscal risk premium remains relatively limited and that EUR/USD could test 1.1100 or even 1.1000 if bond market stress intensifies [1].
Markets are now awaiting further details from Marine Le Pen regarding a counter-budget, which could influence future market direction [1].
CONCLUSION
French bond market turbulence is exerting significant downward pressure on the Euro, with ING warning of further declines in EUR/USD if fiscal risks intensify. The repricing of ECB rate expectations and swap differentials underscores the market's sensitivity to ongoing fiscal developments in France. Investors remain cautious, awaiting further political and fiscal clarity.