
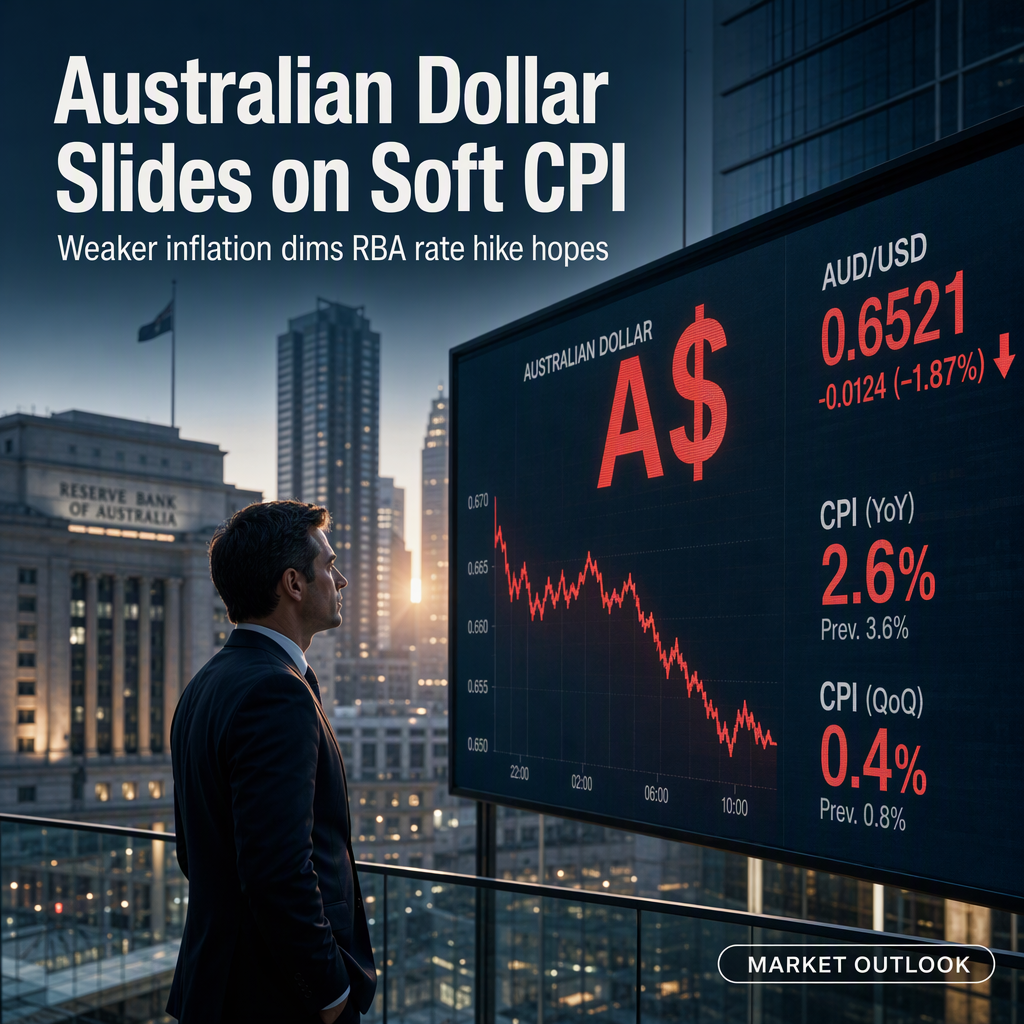
The Australian Dollar has underperformed following the release of August inflation data, which came in weaker than market expectations and weighed on RBA cash rate futures [1]. Headline CPI for August rose by 0.4%, below the consensus estimate of 0.5%, bringing the year-on-year figure to 4.0% (consensus: 4.1%, prior: 3.5%) [1]. The trimmed mean CPI increased by 0.2% month-on-month (consensus: 0.3%), remaining steady at 3.6% year-on-year for the third consecutive month [1]. This subdued inflation profile signals a reduced likelihood of further tightening by the Reserve Bank of Australia, leaving the AUD lagging behind its major peers in the near term [1].
Analyst Elias Haddad at Brown Brothers Harriman notes that the weaker-than-expected inflation print has dampened expectations for additional RBA rate hikes, keeping the Australian Dollar on the back foot [1]. The market implications are clear: the softer CPI data has led to a repricing of RBA cash rate futures, reflecting diminished prospects for monetary tightening [1]. No forward-looking statements or additional analyst opinions regarding future AUD performance or RBA policy were provided in the sources [1].
There is no mention of specific ticker symbols or further market reactions in the articles [1].
CONCLUSION
The Australian Dollar's underperformance is directly linked to weaker August inflation data, which has reduced expectations for further RBA rate hikes. This has led to a repricing in cash rate futures and left the AUD trailing its peers. The market takeaway is a cautious outlook for the Australian Dollar, with diminished prospects for near-term monetary tightening.