
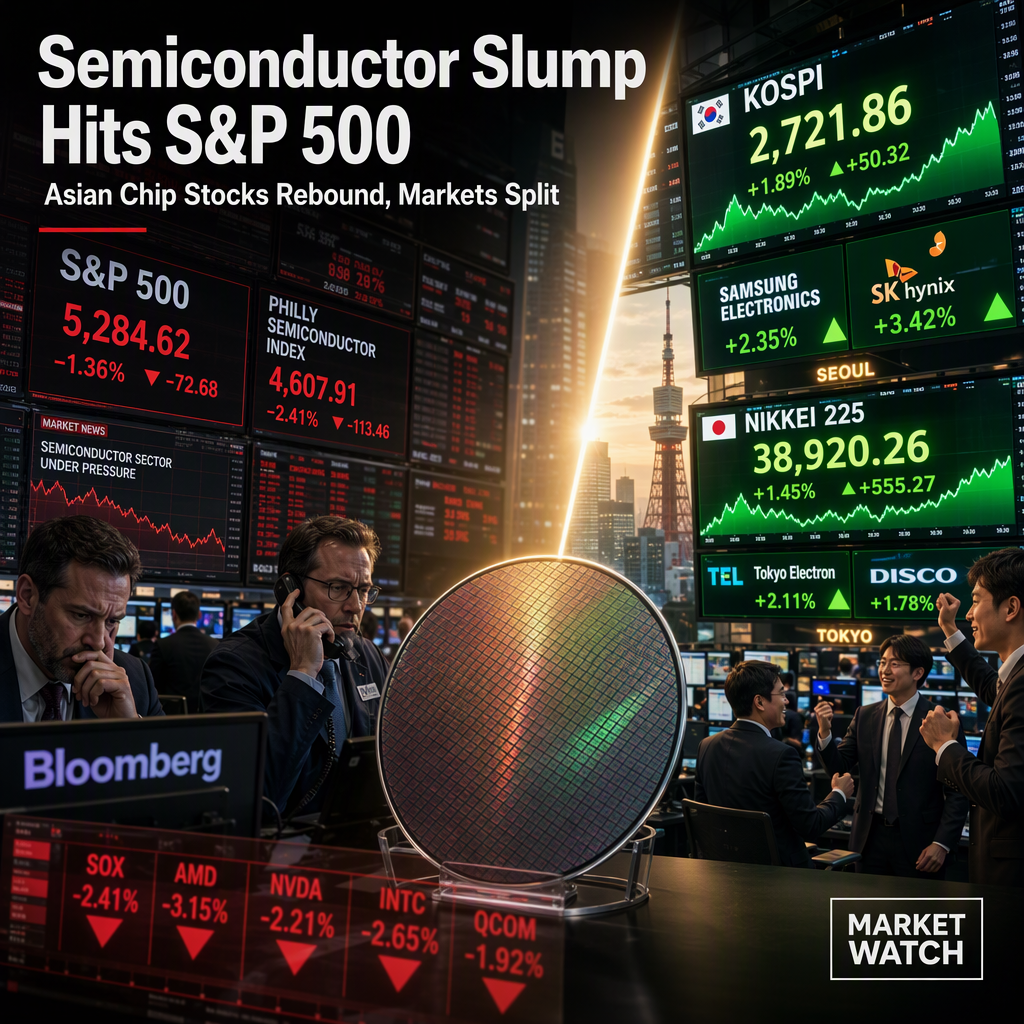
Deutsche Bank strategists report that the S&P 500 closed marginally lower, with a decline of -0.02%, as weakness in semiconductor and data-center stocks exerted downward pressure on equities. The Philly semiconductor index fell by -0.23%, marking its fifth consecutive decline—the first such streak since July. This sector-specific slump had a pronounced effect on the broader index, as semiconductors and semiconductor equipment constitute over a sixth of the S&P 500, amplifying the impact of their moves on the overall market performance [1].
European equities also experienced a slight downturn, with the STOXX 600 falling -0.10% [1]. In contrast, Asian equity markets showed resilience, with most indices trading higher as semiconductor stocks rebounded from their recent selloff. South Korea’s KOSPI led regional gains with a rise of +1.13%, buoyed by a recovery in chipmakers. Japan’s Nikkei advanced by +0.89%, and Hong Kong’s Hang Seng was up +0.16%. However, Australia’s S&P/ASX 200 declined by -0.66%, and China’s CSI 300 fell -0.31%, while the Shanghai Composite hovered near flat, up just +0.01% [1].
Looking ahead, futures for the S&P 500 (+0.22%), Nasdaq 100 (+0.24%), and Stoxx (+0.34%) were trading higher, suggesting a potential rebound in Western markets following the Asian session’s positive momentum in chip stocks [1].
CONCLUSION
Semiconductor sector weakness has recently weighed on major equity indices, particularly the S&P 500, due to the sector's significant index weighting. However, a rebound in Asian chip stocks and positive futures suggest potential stabilization or recovery in global equities.