
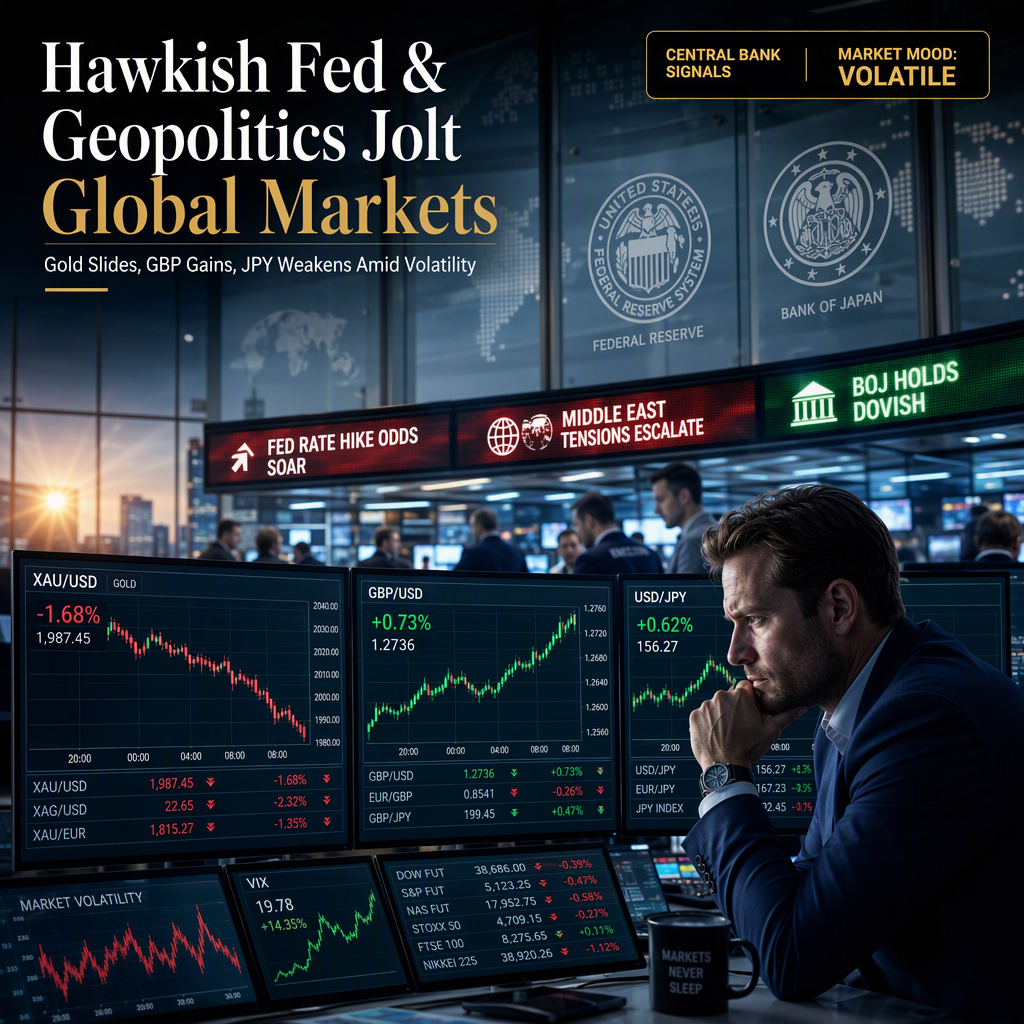
The US Federal Reserve's hawkish stance and persistent inflation concerns have triggered significant moves across major financial markets. Gold (XAU/USD) dropped to around $4,215 during early Asian trading hours on Monday, pressured by a stronger US Dollar and expectations of higher-for-longer US interest rates. Fed officials, including Cleveland Fed President Beth Hammack and Fed Governor Michael Barr, emphasized the need for additional rate increases to curb inflation, with Hammack stating that inflation risks remain high and restrictive monetary policy should be maintained. The implied probability of an October rate hike rose to over 70%, reinforcing headwinds for gold, which typically suffers when yields rise and the dollar strengthens. Technical analysis shows gold maintaining a bearish tone below the 100-day SMA, with immediate support at $4,218 and resistance at $4,300 and $4,340. Strategists at OCBC note that oil and rates response remain key swing factors for gold's near-term direction, with easing energy prices or a softer dollar potentially stabilizing the metal, while further yield increases would keep the bias under pressure [1].
In currency markets, the British Pound (GBP/USD) gained for the second consecutive day, trading around 1.3230 during the Asian session. Despite hawkish Fed signals, the US Dollar weakened, supporting the Pound. Money markets now price in a 65.9% chance of a benchmark rate hike at the October Fed meeting, up from 57.6% a week ago and 9.4% a month ago. Geopolitical tensions in the Middle East, including President Trump's rejection of Iran's proposal to reopen the Strait of Hormuz and the possibility of further military strikes, are also influencing market sentiment. The Pound is further supported by hawkish rhetoric from Bank of England officials, with Governor Andrew Bailey warning that persistently high energy prices could make it difficult to maintain current interest rates. MPC members Sarah Breeden and Clare Lombardelli signaled readiness to back a rate hike if inflation risks persist. Bailey's speech, scoring 8.2/10 on FXS Speechtracker, highlights a cautious bias toward future tightening and introduces a constructive narrative for UK productivity and growth, though GBP remains sensitive to incoming inflation and energy data [2].
The Japanese Yen (USD/JPY) drifted lower, climbing to the 157.75 area during the Asian session, as the US Dollar regained positive traction following the release of Bank of Japan (BoJ) Minutes. The BoJ minutes showed members agreed financial conditions are accommodative and that firms are steadily passing on rising raw material costs, keeping inflation elevated. Despite speculation about possible intervention to support the Yen, the currency reacted little, with the path of least resistance for USD/JPY remaining to the upside amid the BoJ's dovish tone. Technical analysis indicates USD/JPY reclaimed the 23.6% Fibonacci retracement level, with resistance at 159.08 and support at 157.62 and 157.17. Traders are awaiting further developments in the Middle East crisis and speeches from influential FOMC members for short-term opportunities, but the fundamental backdrop favors USD bulls and supports an extension of the USD/JPY uptrend [3].
Across all markets, the interplay between hawkish Fed signals, elevated US bond yields, and geopolitical tensions is driving volatility and shaping investor expectations for further policy tightening. While gold faces headwinds from a strong dollar and rising yields, GBP is buoyed by both US dollar weakness and hawkish BoE rhetoric, and JPY remains under pressure amid dovish BoJ policy and a bullish USD.
CONCLUSION
The hawkish outlook from the US Federal Reserve and ongoing geopolitical tensions have led to pronounced moves in gold, GBP, and JPY markets, with gold under pressure, GBP gaining, and JPY weakening. Market participants are closely watching central bank signals and geopolitical developments for further direction. The prevailing sentiment favors continued volatility and a bias toward USD strength, with rate hike expectations and energy prices as key swing factors.