
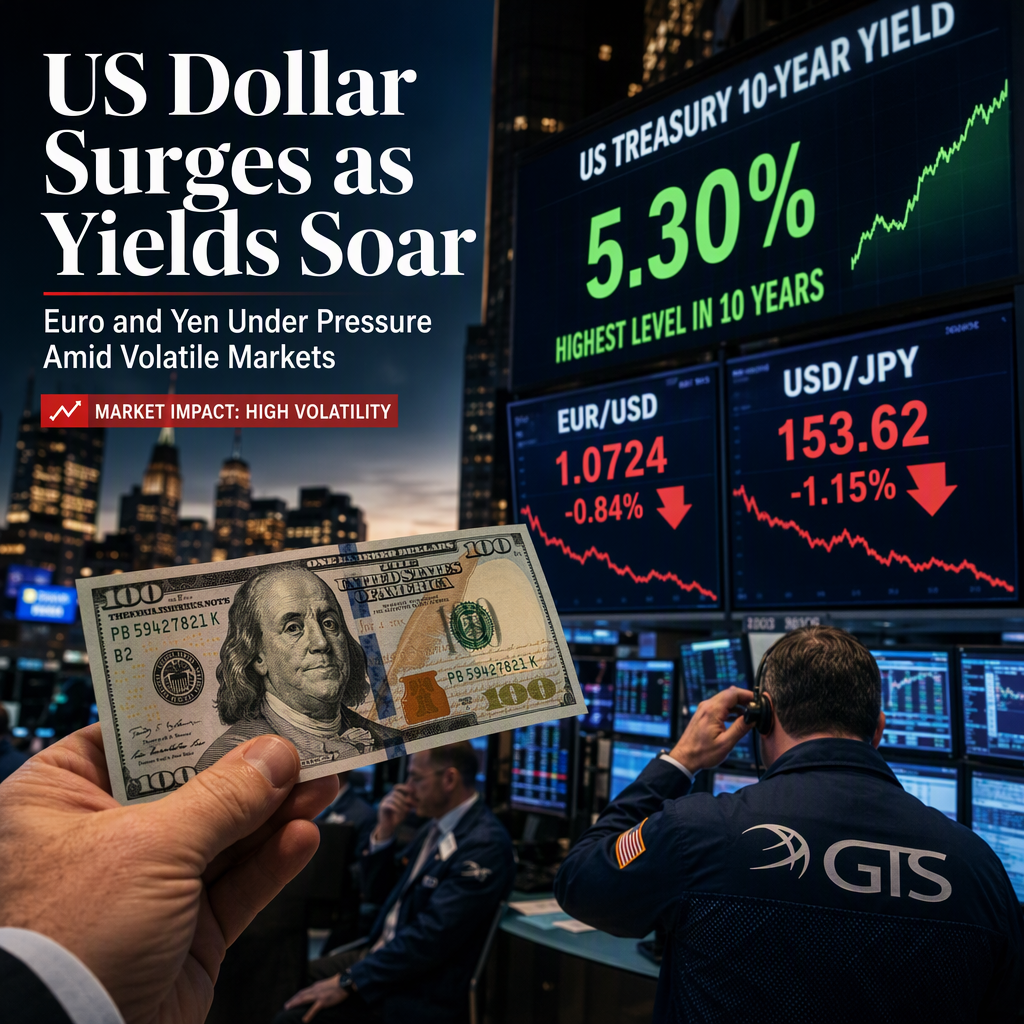
On Thursday, the US Dollar (USD) continued to outperform major currencies, driven by surging US Treasury yields, which reached fresh highs near 5.30% for the 10-year note—the highest level seen in two decades [1][3]. The US Dollar Index (DXY) hovered close to its yearly high of 101.80, maintaining strength against rivals such as the Euro (EUR) and Japanese Yen (JPY) [1][2][3]. The EUR/USD pair traded at around 1.1310, down 0.16% during the European session, with technical analysis indicating a bearish bias and oversold conditions, as the spot price remained below the 20-period EMA at 1.1448 and the RSI at 21.8 [1]. The immediate resistance for EUR/USD was noted at 1.1325, with further resistance at the 20-period EMA [1].
The USD was the strongest against the Japanese Yen and Swiss Franc this week, with percentage changes of 0.59% and 1.05% respectively [2]. Against the Euro, the USD gained 0.52% over the week [2]. The USD/JPY pair advanced beyond 158.00, nearing a one-month high above 159.00, as higher US yields offset hawkish opinions from the Bank of Japan (BoJ) and muted the impact of soft US inflation numbers [3]. BoJ policymakers noted moderate economic recovery and inflation nearing the 2% target, with some advocating for faster monetary tightening; however, these comments had limited effect on the Yen due to the global bond sell-off and rising US yields [3].
Recent US economic data included a private sector employment increase of 90K in September, surpassing expectations of 70K, and a GDP growth revision for Q2 to 2.2% from 1.5% [2]. The core Personal Consumption Expenditures (PCE) Price Index rose 3% year-on-year in August, below the expected 3.3% [2][3]. Analysts at Societe Generale observed that while core PCE undershot expectations, underlying price pressures remain firm, and growth revisions were more significant than inflation revisions [2][3]. They concluded that a pause in the Fed's October meeting remains possible, but an October rate hike is still on the table pending further CPI and PPI data [3]. TD Securities also expects the Fed to lift rates in October but does not rule out a more gradual approach [1].
Market participants are now focusing on upcoming data releases, including the flash Eurozone HICP for September and US ISM Manufacturing PMI, as well as speeches from ECB and Fed policymakers [1][2]. The Euro remains under pressure despite stronger-than-expected preliminary German HICP data for September [1].
CONCLUSION
The US Dollar's strength, fueled by soaring Treasury yields and robust economic data, has exerted significant downward pressure on both the Euro and Japanese Yen. Despite softer US inflation readings, analysts and banks remain divided on the likelihood of a Fed rate hike in October, with upcoming data releases set to influence market direction. Overall, the market impact is high, with continued volatility expected as investors await further economic signals.