
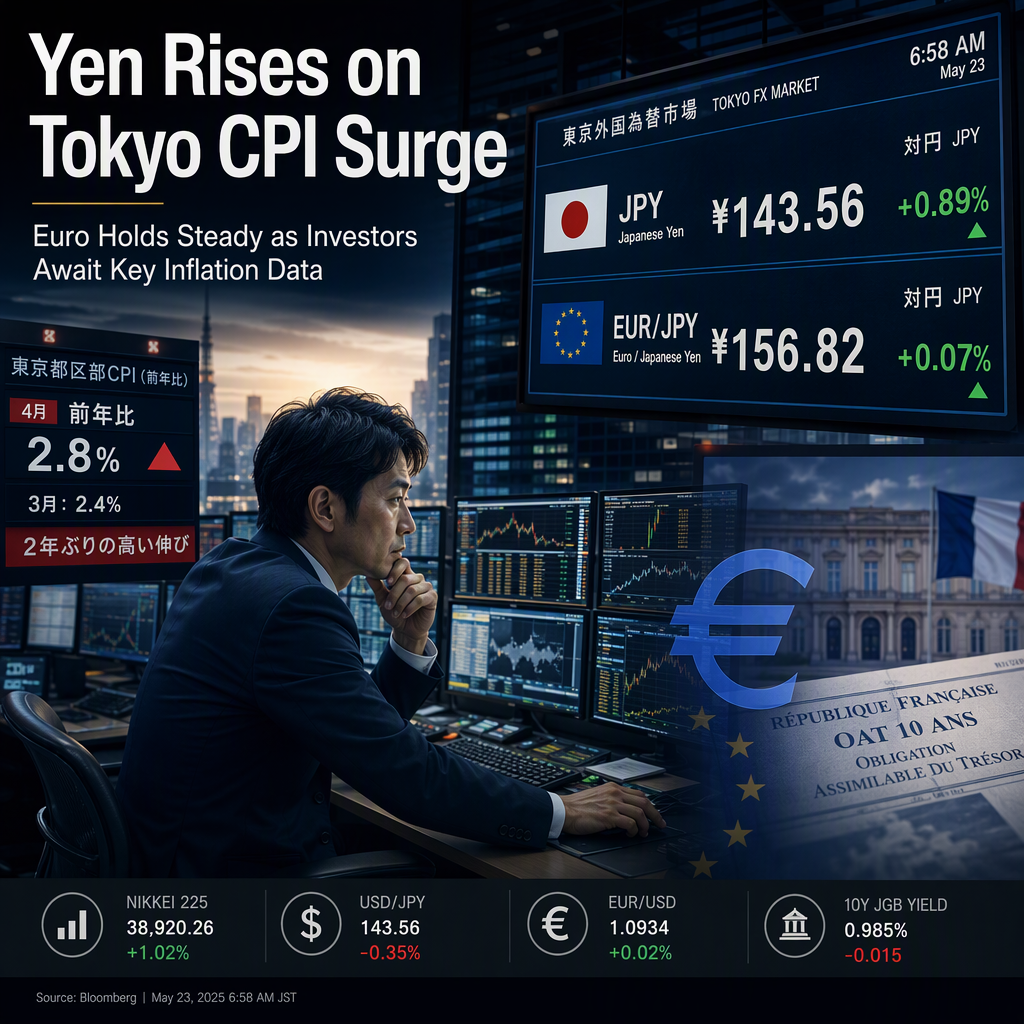
The Euro (EUR) traded flat against the Japanese Yen (JPY) at around 177.60 during the Asian trading session on Friday, remaining close to its recent over 10-month low of 176.66 posted the previous day [1]. The Japanese Yen broadly outperformed other major currencies on Friday, with the JPY showing a 0.08% gain against the US Dollar and a 0.04% gain against the Euro, according to the latest currency heat map [1].
This strength in the Yen was attributed to stronger-than-expected Tokyo Consumer Price Index (CPI) data for September. The Tokyo CPI excluding fresh food rose 2.7% year-on-year, surpassing both the 2.4% estimate and the previous reading of 1.8%. Headline inflation also accelerated to 2.7% from 1.9% in August [1]. These figures reinforced expectations of further interest rate hikes by the Bank of Japan (BoJ) in the near term. The BoJ's Summary of Opinions from the September policy meeting indicated that several policymakers supported tightening monetary conditions further, emphasizing the need to anchor underlying inflation near 2% [1].
Meanwhile, the Euro's cautious trading was influenced by rising government bond yields in France, driven by concerns over accelerating public debt. France's public debt now stands at 119% of GDP, pushing 10-year French bond yields to 4.96%, the highest level since August 2002 [1]. In response, France’s Finance Minister Roland Lescure pledged to restore fiscal discipline, targeting a reduction in the budget deficit from 5% of economic output next year to the European Union limit of 3% by 2029 [1].
Investors are also awaiting the release of Eurozone Harmonized Index of Consumer Prices (HICP) data, which could further influence EUR/JPY dynamics [1].
CONCLUSION
The Japanese Yen's strength is underpinned by robust Tokyo inflation data and expectations of further BoJ tightening, while the Euro remains subdued amid French fiscal concerns and anticipation of key Eurozone inflation data. Market participants are closely watching upcoming economic releases for further direction.