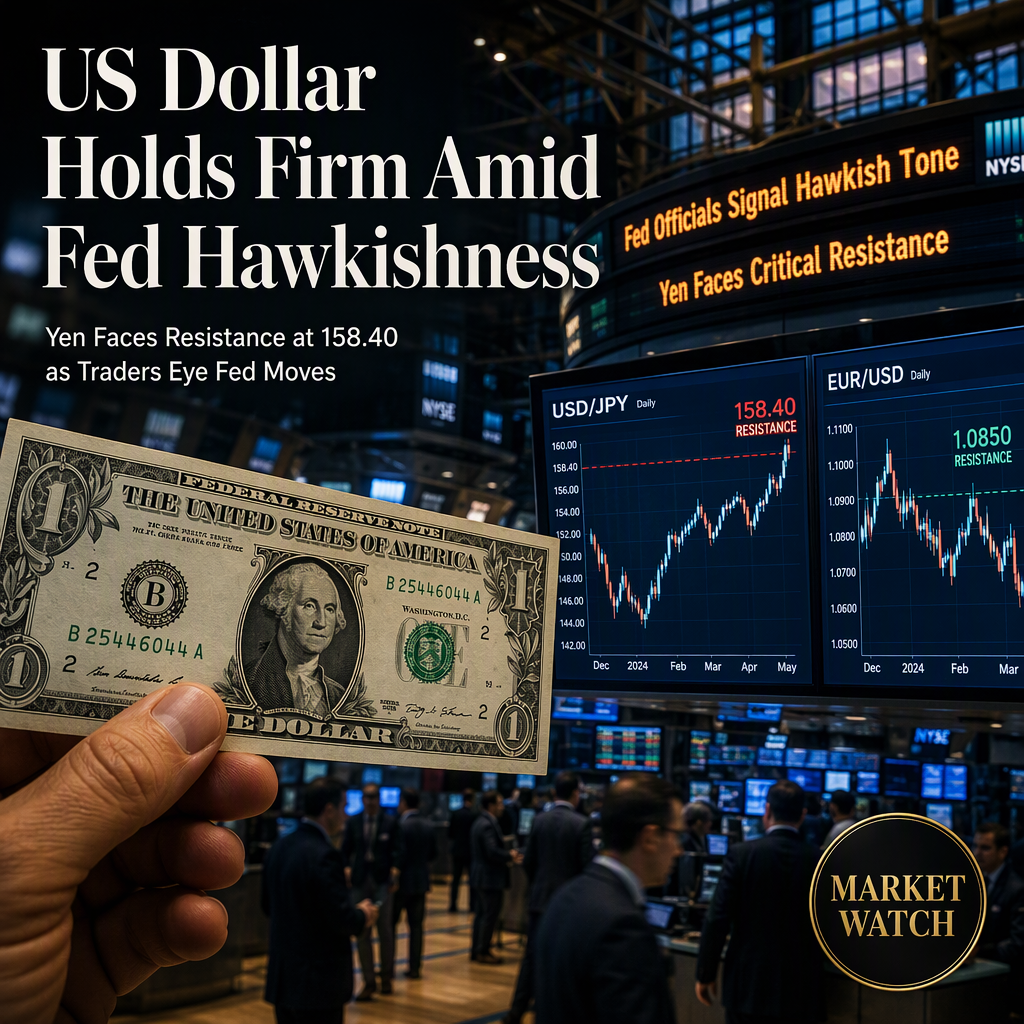
The US Dollar (USD) has demonstrated resilience into the year-end, supported by hawkish commentary from Federal Reserve officials, according to OCBC strategists Sim Moh Siong and Christopher Wong [1]. Despite an improved risk appetite driven by a tech-led equity rally, optimism around US-China talks, and lower oil prices, the USD traded mixed rather than weaker. Falling energy prices have helped reduce near-term inflation worries and pushed global yields lower, but hawkish statements from Fed officials such as Chicago Fed President Goolsbee and St. Louis Fed President Musalem have limited the drop in US front-end yields, providing ongoing support for the USD [1]. OCBC maintains a modestly stronger USD outlook through year-end, citing ongoing Fed tightening risks and continued challenges for European currencies, particularly the euro, which faces fiscal concerns in France and elevated energy costs [1].
In the context of the Japanese Yen (JPY), United Overseas Bank (UOB) analysts Quek Ser Leang and Lee Sue Ann report that the USD/JPY pair remains supported after testing the 157.30 area, with short-term price action expected to stay within a 156.90–157.80 range [2]. Over the next 1–3 weeks, they see room for further USD strength, but note that overbought conditions could limit gains near the 158.40 resistance level [2]. The bullish outlook for USD/JPY remains intact as long as the USD holds above the key support level at 156.20 [2]. On the previous day, the USD rose to a high of 157.52 before closing at 157.36, marking a 0.32% increase, though upward momentum has not significantly increased [2].
Both sources highlight the ongoing support for the USD, with OCBC emphasizing macroeconomic and policy factors such as Fed hawkishness and global risk sentiment, while UOB focuses on technical levels and short-term trading ranges for USD/JPY [1][2]. OCBC also notes that a more meaningful USD rally would require clearer evidence of demand-driven inflation, rather than inflation stemming from supply-side pressures [1].
Looking ahead, market participants are closely watching comments from New York Fed President Williams, especially after his participation in last week's rate hike decision, as his views could influence expectations for further Fed policy moves [1].
CONCLUSION
The US Dollar continues to find support from hawkish Fed commentary and ongoing global uncertainties, with analysts expecting modest strength into year-end. Technical analysis suggests further USD gains against the Japanese Yen are possible, though resistance at 158.40 may cap advances in the near term. Market attention remains focused on upcoming Fed communications and evolving macroeconomic conditions.