
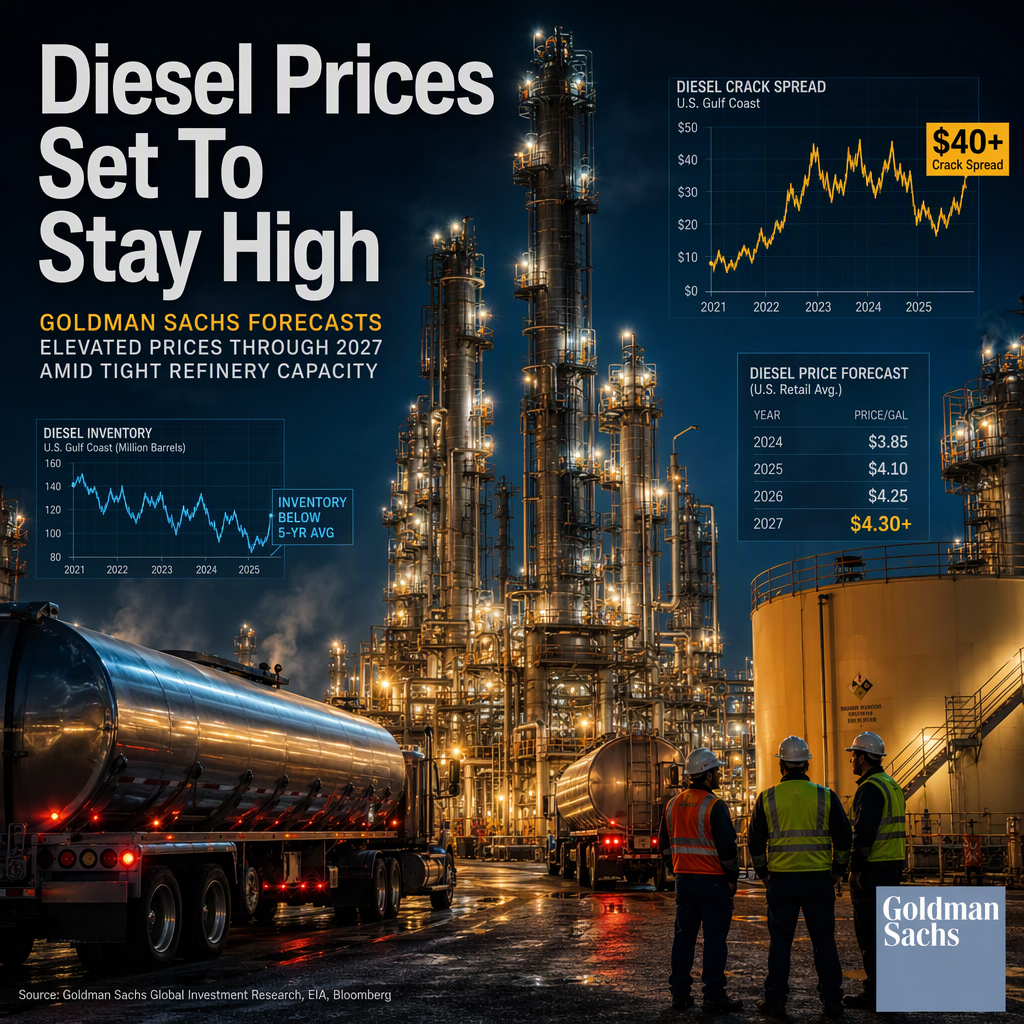
Goldman Sachs has projected that diesel prices may need to remain high through 2027 due to ongoing refinery constraints and depleted inventories, even as demand from governments and companies recovers [1]. Nikhil Bhandari, Goldman's co-head of Asia-Pacific natural resources research, stated that high product prices are necessary to ensure continued demand destruction into next year, preventing recovering demand from overwhelming the limited refining capacity [1]. The bank forecasts that global diesel and jet-fuel crack spreads will average above $40 per barrel in 2027, more than double the typical level of around $20, despite Brent crude prices expected to stabilize at approximately $80 per barrel as crude flows through the Strait of Hormuz normalize [1].
Goldman Sachs anticipates that if there is any rebound in demand next year, the global refining system will need to reach its highest utilization rate in the past two decades [1]. The bank also expects 2026 to be another year of negative refining capacity growth, with refining capacity outside China projected to contract by about 300,000 barrels per day [1]. Product inventories could end 2026 below the lowest days-of-supply level recorded since 2015, according to Goldman's global Refining Super Cycle report [1].
Additional supply pressures include roughly 2 million barrels per day of Middle Eastern refining capacity remaining offline and damaged Russian facilities further restricting diesel supply [1]. U.S. refineries, which have been operating at elevated rates to offset falling capacity, will also need to undergo deferred maintenance, temporarily reducing refinery runs [1]. The recovery of Gulf crude exports is not expected to significantly improve refined product availability, as shipments of diesel, gasoline, and jet fuel remain restricted [1].
Baden Moore, a resources and energy research analyst at CLSA, noted that recent weakness in demand does not necessarily indicate permanently lost demand, as buyers have managed the market through inventory management, reserve drawdowns, consumption curtailment, and refinery optimization [1]. Moore added that replenishing global inventories while meeting demand could take up to two years [1].
The Group of Seven countries recently agreed to release 100 million barrels of crude and refined products over four months, including a substantial diesel release within the first 20 days, in an effort to address supply constraints [1].
CONCLUSION
Goldman Sachs expects diesel prices to remain elevated through 2027 due to persistent refinery constraints and low inventories, with crack spreads forecasted to stay well above historical averages. Market participants should anticipate continued supply tightness and high utilization rates, while inventory replenishment may take up to two years. The recent G7 release of crude and refined products aims to provide some relief, but significant challenges remain.