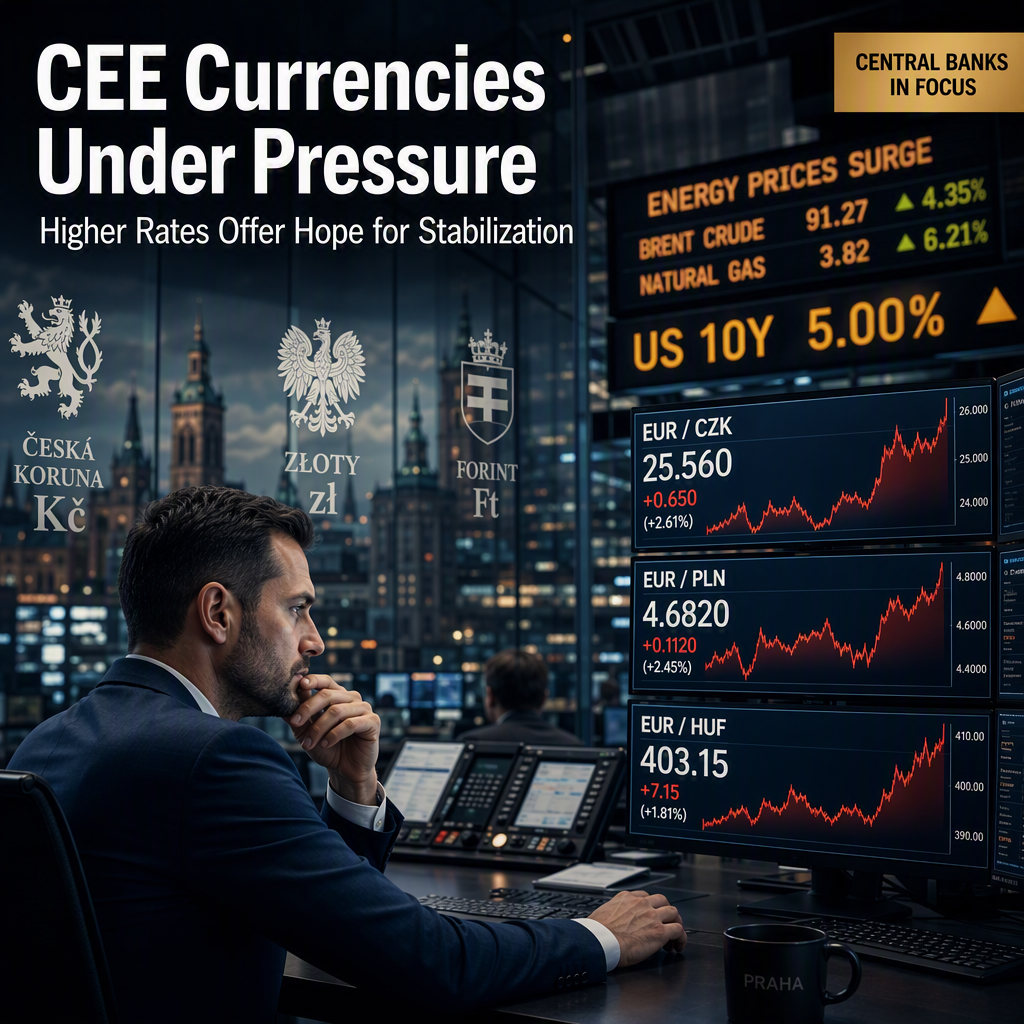
According to ING’s Frantisek Taborsky, Central and Eastern European (CEE) currencies experienced significant pressure following a post-weekend surge in energy prices, a jump in the US 10-year Treasury yield to 5%, and a stronger US dollar. These factors led to a sharp repricing of rates higher across the curve in CEE markets, with front-end markets in the CEE3 pricing in an additional 10-20 basis points of rate hikes on average [1].
Despite the prevailing risk-off sentiment, Taborsky suggests that higher front-end rates should help cushion CEE currencies against further losses and create scope for stabilization. He maintains a broadly unchanged view on EUR/CZK, expecting the pair to approach Thursday’s Czech National Bank (CNB) meeting near 24.300, with potential for further upside if the central bank adopts a dovish tone versus market pricing [1].
The EUR/PLN rate differential saw the region’s largest increase, and Taborsky notes that the zloty could stabilize below 4.340 as markets look through dovish comments from Monetary Policy Council (MPC) members following the National Bank of Poland (NBP) decision [1].
EUR/HUF remains vulnerable due to its high sensitivity to gas prices, and may rise further. With the Hungarian market still pricing in roughly one rate cut, the forint could again test levels above 368. Support for the currency may not emerge until next week’s National Bank of Hungary (NBH) meeting, which is seen as carrying hawkish risks [1].
CONCLUSION
CEE currencies have come under pressure from global shocks, but higher local rates are expected to provide some stabilization. While risk-off sentiment persists, analysts see potential for EUR/CZK and EUR/PLN to stabilize, though EUR/HUF remains vulnerable until the upcoming NBH meeting. The market is closely watching central bank actions for further direction.