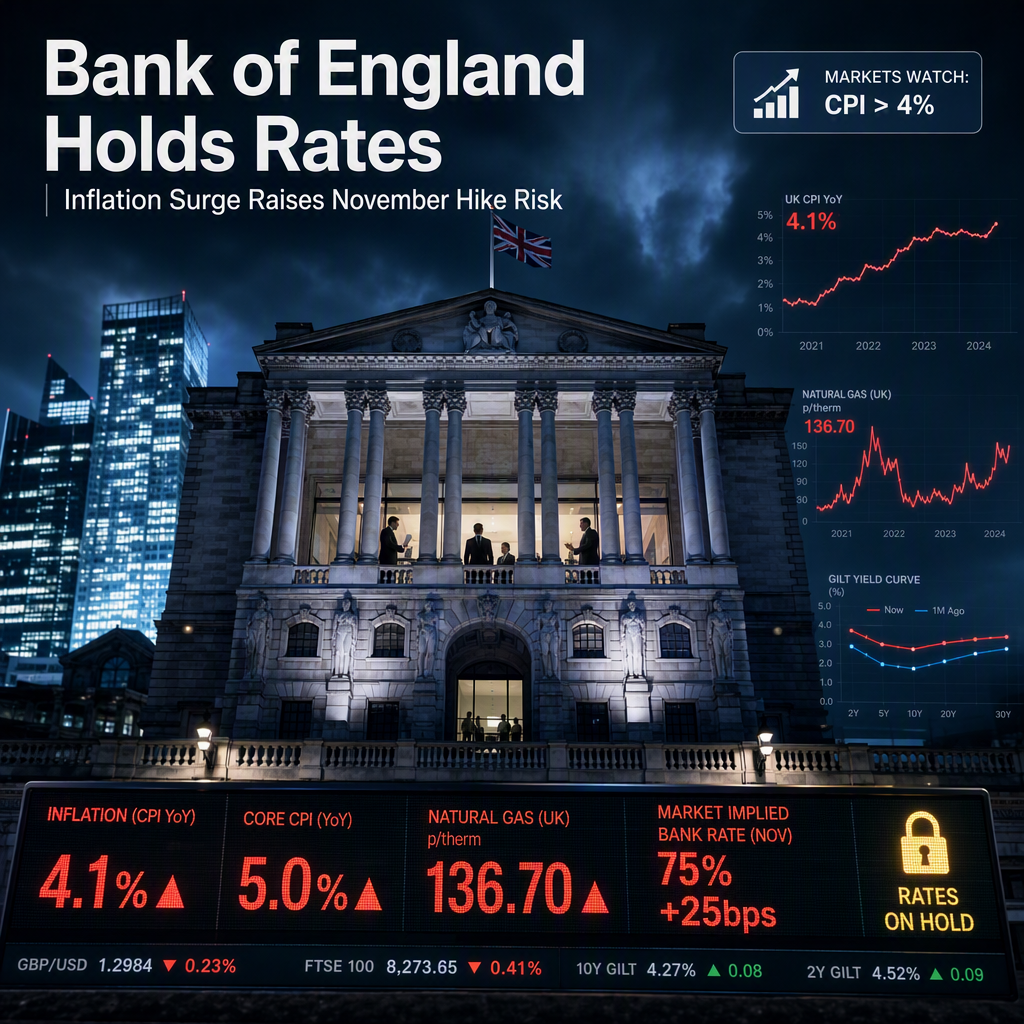
The Bank of England (BoE) is expected to keep interest rates on hold at its upcoming monetary policy announcement, according to MUFG’s Derek Halpenny, but the risk of a rate hike in November is increasing due to mounting inflation pressures in the United Kingdom [1]. Surging natural gas prices, with front futures up nearly 100% since July, are anticipated to drive a significant increase in the OFGEM utility price cap in January, pushing the annual Consumer Price Index (CPI) above 4.0% [1]. The year-on-year CPI for August was confirmed at 3.1%, exceeding the BoE’s forecast of 2.8% [1].
MUFG notes that while only 2 basis points of hikes are priced in for the current meeting, the previous BoE vote was split 6-3, and a closer 5-4 vote is possible this time, suggesting the market may be underestimating the risk of a pre-emptive hike [1]. A 'hawkish hold'—where the BoE signals a likely rate increase in November—could put modest upward pressure on front-end yields as markets begin to price in back-to-back hikes, currently reflecting 39 basis points by December [1].
Despite the potential for a stronger pound following a hawkish hold, MUFG remains skeptical about significant upside for the currency before the UK budget announcement on October 28th [1]. The focus remains on how the BoE will respond to persistent inflationary pressures, particularly from the energy sector, in the coming months [1].
CONCLUSION
The Bank of England is expected to hold rates for now, but rising inflation and energy prices are increasing the likelihood of a November rate hike. While a hawkish hold could support the pound and front-end yields, significant currency gains may be limited until after the UK budget. Market participants are advised to monitor upcoming BoE communications and inflation data closely.