
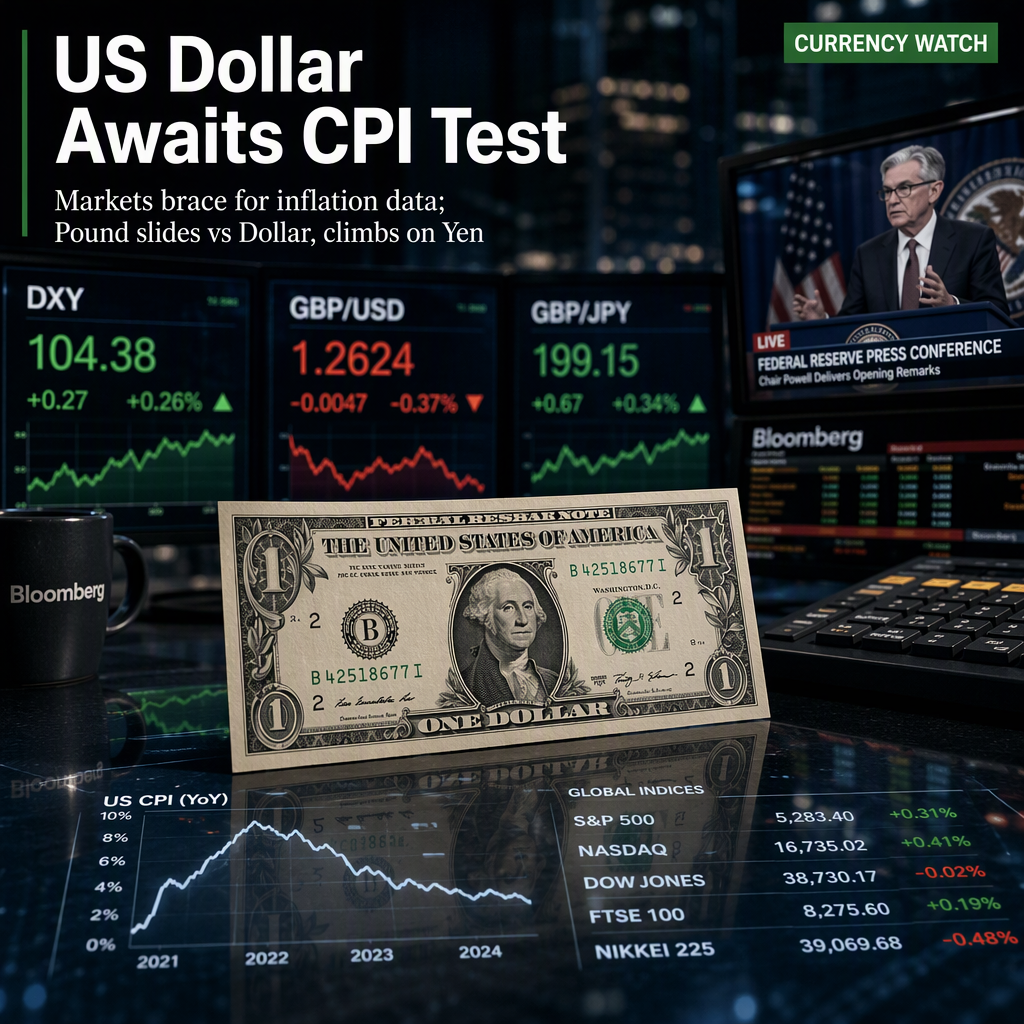
The US Dollar Index (DXY) is consolidating at higher levels, trading just above 102.00, as softer US economic data and cautious Federal Reserve (Fed) communication have led markets to scale back expectations for an immediate rate hike this month [1]. As of Monday's European session, the DXY was up 0.15% to near 102.38 [2]. The upcoming US Consumer Price Index (CPI) report for September, due Wednesday, is seen as a pivotal event that could confirm whether the Fed will pause rate hikes this month, with a potential for another increase in December if inflation surprises to the upside [1][2]. Market estimates suggest headline US inflation accelerated to 3.7% year-on-year from 3.4% in August, while core CPI is expected at 2.5% year-on-year, up from 2.4%. On a monthly basis, headline CPI is forecast to rise 0.6%, compared to the previous 0.4% [2].
Recent comments from Fed officials have highlighted concerns about persistently high inflation, reinforcing the market's focus on the CPI data [2]. Unless there is a significant upside surprise in underlying inflation, analysts at MUFG expect the Fed to leave rates unchanged this month, with a likely temporary pause before a possible hike in December [1].
The British Pound (GBP) erased early gains against the US Dollar, with GBP/USD trading flat around 1.3235 as the Dollar recovered morning losses and turned positive [2]. Technical analysis shows GBP/USD remains bearish in the near term, trading below the 20-period EMA at 1.3290, with the Relative Strength Index (RSI) near 39, indicating weak but stabilizing downside momentum [2]. Investors are also awaiting UK GDP data for August, expected to show a 0.1% contraction after July's 0.4% growth, as well as upcoming Manufacturing and Industrial Production figures [2].
In contrast, the British Pound extended gains against the Japanese Yen (JPY), with GBP/JPY trading just below 210.00, buoyed by concerns over Japan's high public debt and weak domestic demand, as well as rising oil prices [3]. The Yen weakened further after Japanese household spending declined for the ninth consecutive month in August [3]. Technical indicators for GBP/JPY remain bullish, with resistance seen at the 211.00 area and support at 209.00 and 207.00 [3].
On the geopolitical front, a recovery in oil prices and news of a ceasefire between Ukraine and Russia, along with US President Donald Trump's announcement of increased Russian diesel exports and a temporary easing of US sanctions, have supported the US Dollar by alleviating some global energy supply concerns [2].
CONCLUSION
The US Dollar remains resilient ahead of the key US CPI release, with markets largely expecting the Fed to pause rate hikes this month unless inflation data surprises to the upside. The British Pound is under pressure against the Dollar but continues to strengthen versus the Yen amid Japanese economic concerns. Market participants are closely watching upcoming US and UK economic data for further direction.