
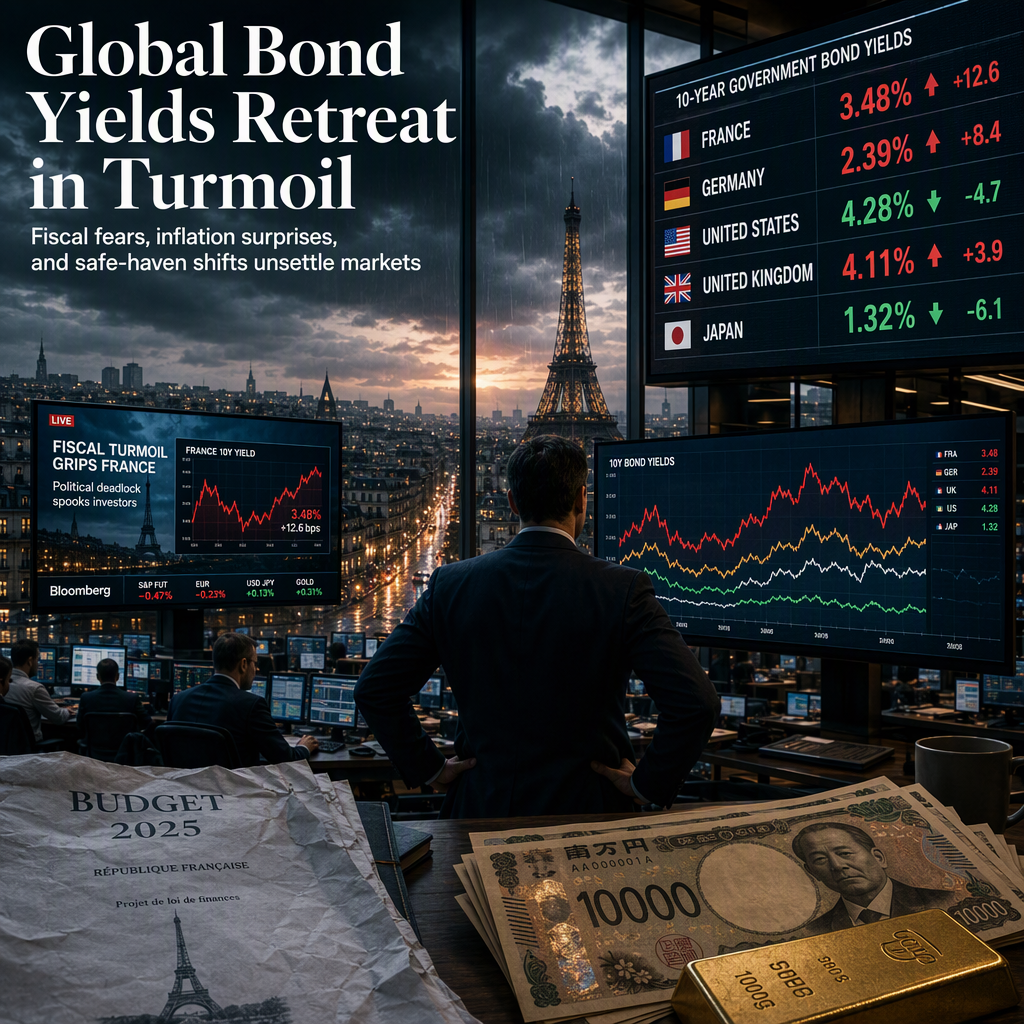
Global bond markets experienced significant volatility as concerns over France’s fiscal and political stability drove a surge in French government bond yields, while safe-haven demand led to a pullback in US and German yields [1][3]. France’s 10-year OAT yield surpassed 4.9%, reaching its highest level since July 2002 after the government introduced a budget deficit reduction plan. However, France’s fiscal watchdog warned that the economic forecasts underpinning the plan were overly optimistic, fueling further market anxiety [1]. In contrast, Germany’s 10-year Bund yield slipped to around 3.47% as investors balanced safe-haven flows with expectations of continued ECB rate hikes through 2027 [1].
The US 10-year Treasury yield hovered near 5.25%, retreating from multi-decade highs but still at levels not seen since 2002, as expectations for further Federal Reserve tightening persisted [1]. UK 10-year gilt yields also eased below 5.38% after peaking at levels last seen in July 2007, though they remain structurally elevated due to inflation concerns and robust economic growth [1].
In Asia, Japan’s 10-year government bond yield slipped below 3.1%, mirroring the global retreat in yields [1]. The Japanese Yen, however, saw mixed signals regarding its safe-haven status. While the Yen outperformed its peers on Friday, supported by stronger-than-expected Tokyo CPI data (core inflation rose to 2.7% YoY in September from 1.8% in August, beating the 2.4% forecast) [4], Commerzbank analysts noted that rising Japanese debt concerns and Bank of Japan (BoJ) rate hikes are eroding the Yen’s traditional crisis appeal [2]. The BoJ’s Summary of Opinions revealed a majority favoring accelerated monetary tightening, but Cabinet Office representatives urged caution, suggesting any shift toward tighter policy would be gradual [4]. Brown Brothers Harriman’s Elias Haddad described the BoJ’s stance as "hawkish on direction but generally cautious on the pace," limiting near-term upside for the Yen [4].
Gold prices posted modest gains as financial stress in Europe and risk-off sentiment prompted safe-haven flows, with Deutsche Bank noting that the moves were reminiscent of the Euro crisis. The Euro fell 0.76% against the Dollar, and the STOXX Banks index dropped 3.90%, its worst day since March [3].
Analysts at Deutsche Bank observed that tightening financial conditions are increasingly seen as substituting for further ECB rate hikes, reinforcing skepticism about the scope for additional aggressive monetary tightening [1]. Meanwhile, expectations for further ECB rate increases continue to push borrowing costs higher across the euro area, raising concerns about debt sustainability for the bloc’s most indebted nations [1].
CONCLUSION
Global bond markets are under pressure from fiscal and political instability in France, persistent inflation, and shifting central bank expectations. While safe-haven flows have supported US, German, and Japanese bonds, the Japanese Yen’s traditional role as a crisis currency is being questioned amid domestic debt and policy concerns. Market volatility remains elevated, with analysts highlighting skepticism over further aggressive rate hikes and ongoing risks to debt sustainability in Europe.