
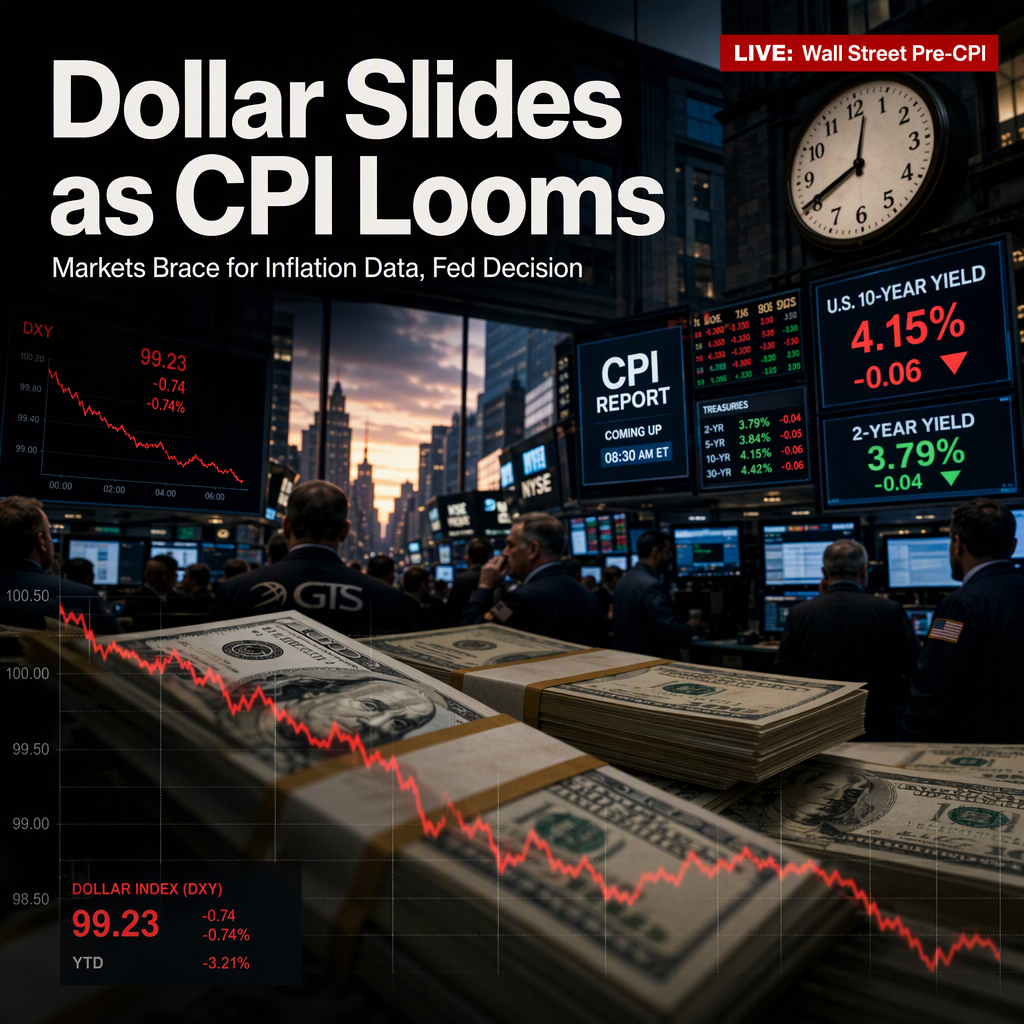
On Wednesday, global financial markets focused on the imminent release of the United States September Consumer Price Index (CPI) data, which is expected to significantly influence Federal Reserve interest rate expectations and broader market sentiment [1][2][3][4]. The US Dollar Index (DXY) weakened to near 102.10 as oil prices eased and US bond yields fell, with the dollar showing its largest decline against the Australian Dollar at -0.25% [2]. Meanwhile, U.S. Treasury yields inched lower, with the benchmark 10-year yield down 2 basis points to 5.195%, the 30-year yield down 1 basis point to 5.549%, and the 2-year note yield down 2 basis points to 4.772% [4].
Economists polled by Dow Jones expect headline inflation to rise 0.6% month-over-month and 3.6% year-over-year, while core inflation is projected to increase 0.2% from August and 2.5% annually [4]. Danske Bank strategists similarly forecast headline inflation at 0.5% m/m SA, 3.6% y/y, and core inflation at 0.2% m/m SA, 2.5% y/y, with energy prices being the main driver of the expected pickup in headline inflation [1][3]. Deutsche Bank analysts emphasized that any surprises in the CPI report will shape the narrative ahead of the Fed's next interest rate decision, as the PCE inflation readings will not be available until after the meeting [4].
Market participants see about a 79% probability that the Fed will leave rates unchanged at its October 27-28 meeting, up from 51% a month ago, but are pricing in an 89.4% chance of an increase at the final meeting of the year in December, according to the CME FedWatch tool [2]. Danske Bank and FXStreet Insights Team note that recent Fed communication signals little urgency to hike again, and only a clear upside surprise in inflation would prompt the Fed to signal a rate hike in October [1][3]. Fed officials, including Waller and Goolsbee, have highlighted that AI-related investment is beginning to spill over into inflation, supporting the case for keeping policy tight in the near term [3].
Elsewhere, silver prices (XAG/USD) declined 0.65% to near $58.70 during the European trading session, pressured by higher oil prices and ongoing tensions in the Middle East, which have stoked supply fears and global inflationary concerns [1]. Technical analysis shows XAG/USD trading below its 20-day EMA at $61.45, with the Relative Strength Index at 37.49, indicating lingering downside pressure [1].
Investors are also awaiting additional US economic data, including the producer price index, retail sales, and initial jobless claims, all due on Thursday [4].
CONCLUSION
Markets are closely watching the September CPI release, which is expected to show a modest uptick in inflation and will be pivotal for the Federal Reserve's upcoming policy decisions. The weakening US Dollar and lower Treasury yields reflect investor caution, while silver prices remain under pressure amid inflationary concerns. Any significant surprise in the CPI data could shift expectations for Fed rate hikes and drive further market volatility.