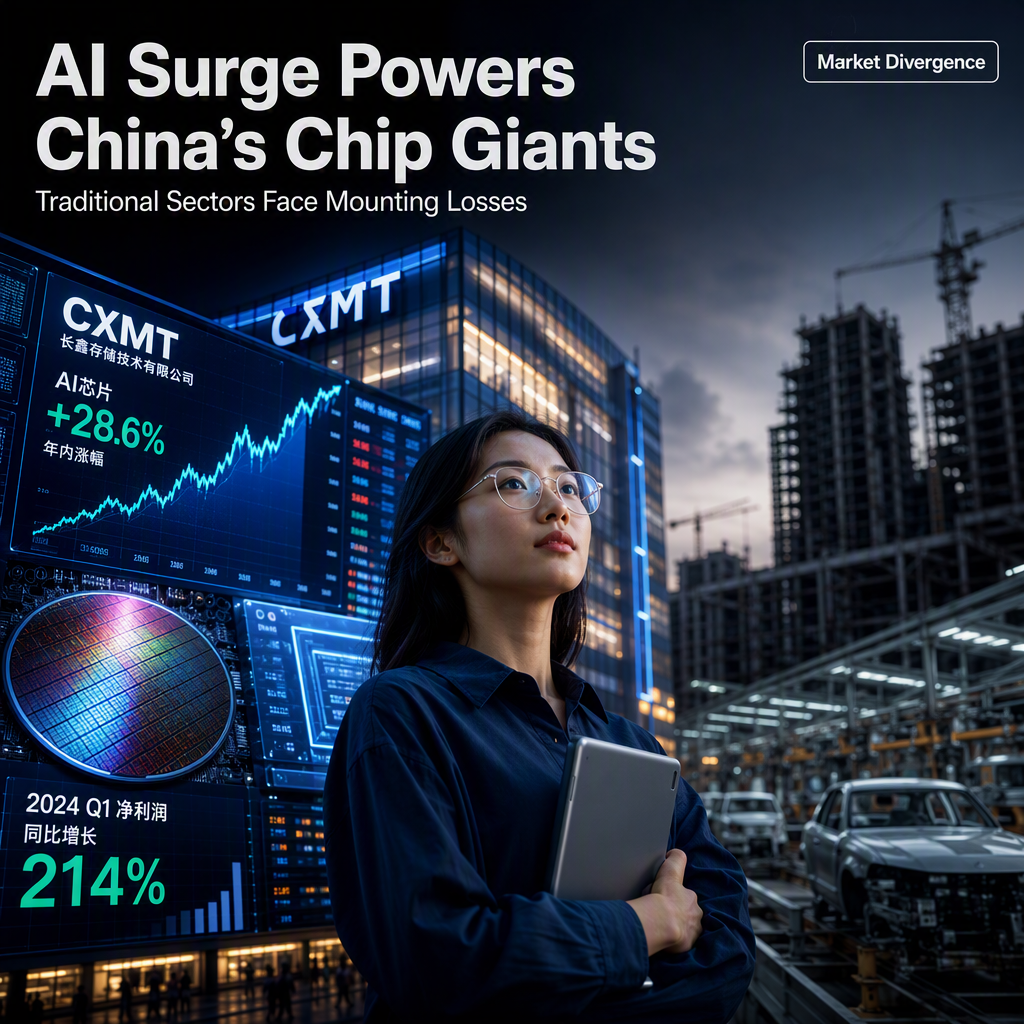
A quarter of China-listed companies reported net losses in the first half of the year, despite the group as a whole achieving approximately 20% net profit growth, according to recent financial disclosures [1]. This overall profit increase was primarily driven by the strong performance of technology and AI-related sectors, with chipmakers such as CXMT experiencing a surge in profits due to heightened demand for AI components [1]. CXMT notably surpassed global competitors SK Hynix and Micron in memory profit margins, highlighting the robust momentum within China's semiconductor industry fueled by AI applications [1].
In contrast, traditional sectors such as real estate and automobile manufacturing faced significant challenges, posting widespread losses amid a persistent slump in domestic demand [1]. Property developers, including Vanke, reported widening losses as new property measures were introduced in Chinese cities to stabilize the market, exacerbating the ongoing debt crunch in the sector and further pressuring investor sentiment [1].
The market is witnessing a pronounced divergence, with technology and AI-related companies thriving while other sectors stagnate or contract [1]. Analysts expect this trend to continue, emphasizing the importance of sector selection for investors navigating China's volatile markets [1]. Market participants are advising a focus on semiconductor and AI sectors, which are demonstrating strong price momentum and positive sentiment, while cautioning that resistance levels for property and automobile stocks are likely to persist unless there is a significant shift in domestic demand or policy direction [1].
CONCLUSION
China's market is increasingly split, with AI and semiconductor companies driving profit growth while traditional sectors like real estate and automobiles face mounting losses. Investors are advised to focus on technology and AI-related stocks, as the divergence between sectors is expected to persist absent major policy changes or a rebound in domestic demand.