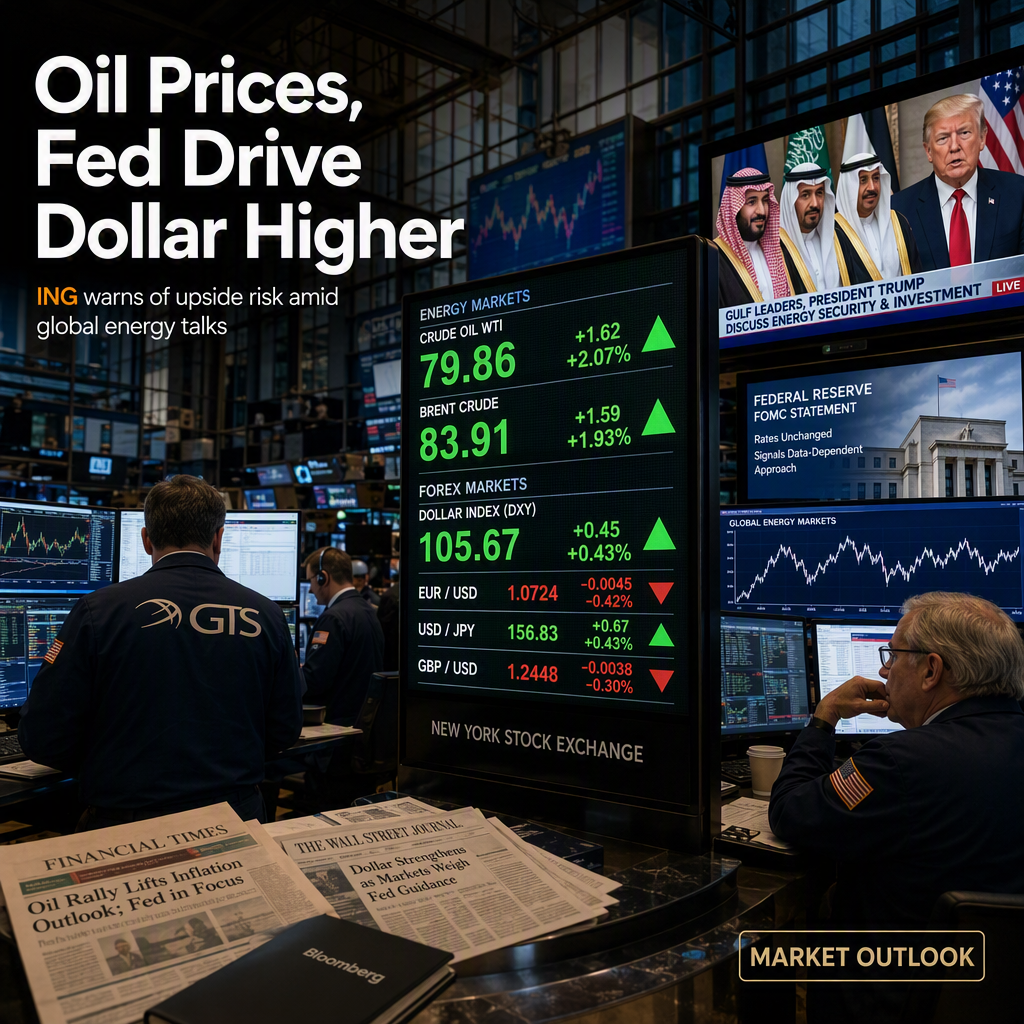
ING strategist Francesco Pesole highlights that moderating oil prices have slightly cooled the US Dollar's momentum following the Federal Reserve's hawkish message, but still sees upside risks for the Dollar in the near term [1]. Oil prices are identified as the main short-term driver for the Dollar, especially during a typical late-month lull in major US economic data releases [1]. Pesole notes that energy markets are optimistic about a reported meeting between US President Donald Trump and Gulf States during the UN General Assembly, which could provide clarity on regional plans. Media speculation suggests Trump is nearing a major decision on whether to escalate military operations or pursue an end to the conflict, but ING does not expect these developments to push Brent crude below $100 per barrel at this stage [1].
The Federal Reserve's hawkish guidance on Wednesday has, according to ING, given markets the green light to fully price in a rate hike in October if incoming data and energy prices support such a move [1]. For the next few days, ING expects oil prices to remain the primary market driver, as today's industrial production and leading index for August are unlikely to attract significant attention, and next week's economic calendar is relatively light [1]. Fedspeak will also be closely watched, with off-meeting remarks by FOMC members becoming more relevant after September's data releases, although the dot plot already signals the Fed's intention to hike again this year [1].
CONCLUSION
ING sees continued upside risks for the US Dollar, driven by oil prices and the Federal Reserve's hawkish stance. With limited major US data releases in the near term, energy markets and Fedspeak are expected to steer Dollar movements. Market participants should monitor oil price developments and Fed communications for further direction.