
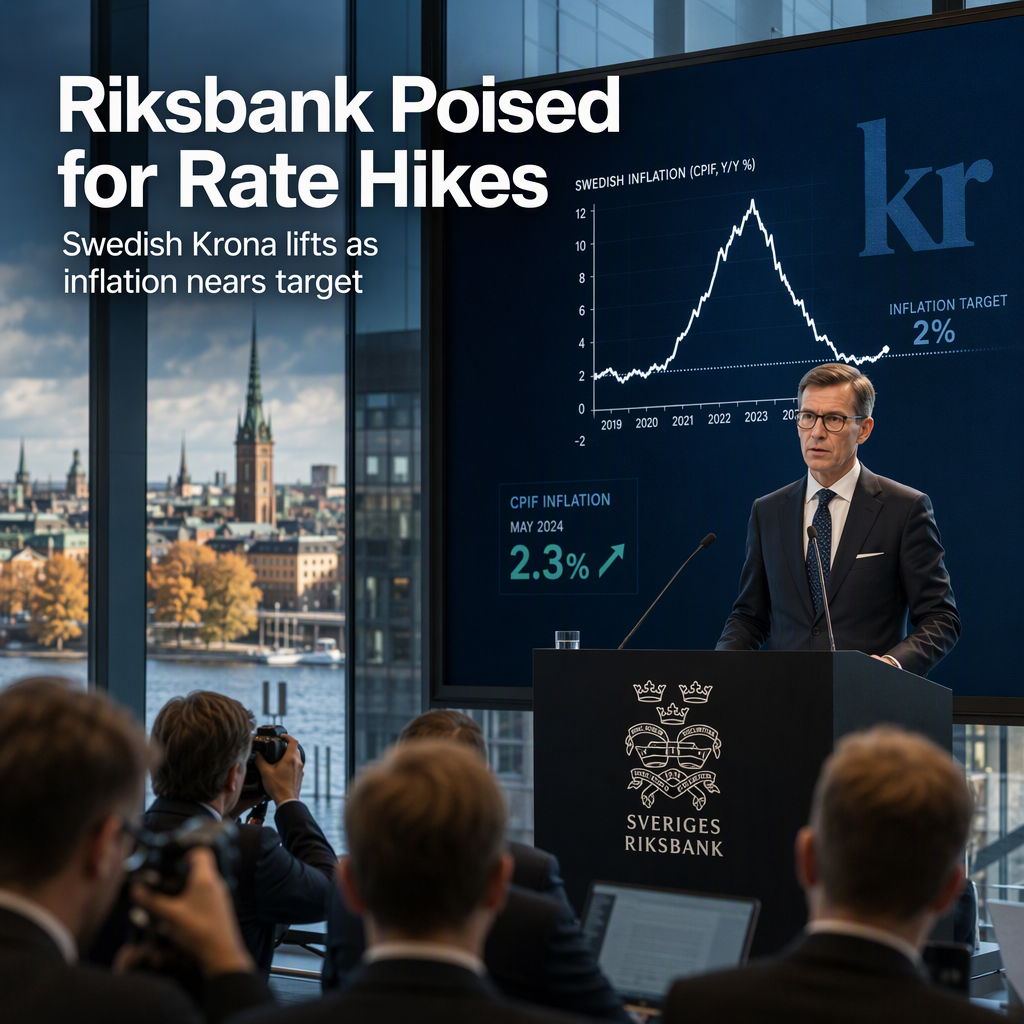
The Swedish Krona (SEK) is currently supported by expectations of further monetary tightening from the Riksbank, despite the USD/SEK pair remaining firm due to broad US Dollar (USD) strength [1]. According to Brown Brothers Harriman’s Elias Haddad, Sweden’s September Consumer Price Index (CPI) data were mixed, with the CPIF matching both consensus and the Riksbank’s projection at 1.5% year-over-year, up from 0.7% in August [1]. However, CPIF excluding energy was cooler than anticipated at 0.5% year-over-year, below the consensus and Riksbank projection of 0.7%, and unchanged from August [1].
When adjusted for temporary fiscal policy measures, Swedish inflation is closer to 2%, which keeps the possibility of a policy rate hike alive [1]. The Riksbank stated in September that 'the policy rate should be raised more going forward than projected in the June forecast' and reiterated its expectation that 'the increases to the policy rate will begin this year' [1].
Looking ahead, the Riksbank’s policy rate forecast implies over 75 basis points of tightening to reach 2.50% in the next twelve months, while the swaps curve is pricing in over 100 basis points of hikes to 2.75% [1]. This anticipated tightening is expected to limit policy divergence with the Federal Reserve and act as a headwind for USD/SEK [1].
CONCLUSION
The Riksbank’s guidance and market pricing for significant rate hikes are supporting the Swedish Krona, despite current USD strength. With inflation near target and further tightening expected, policy divergence with the Federal Reserve is likely to remain limited, posing a challenge for further USD/SEK gains.