
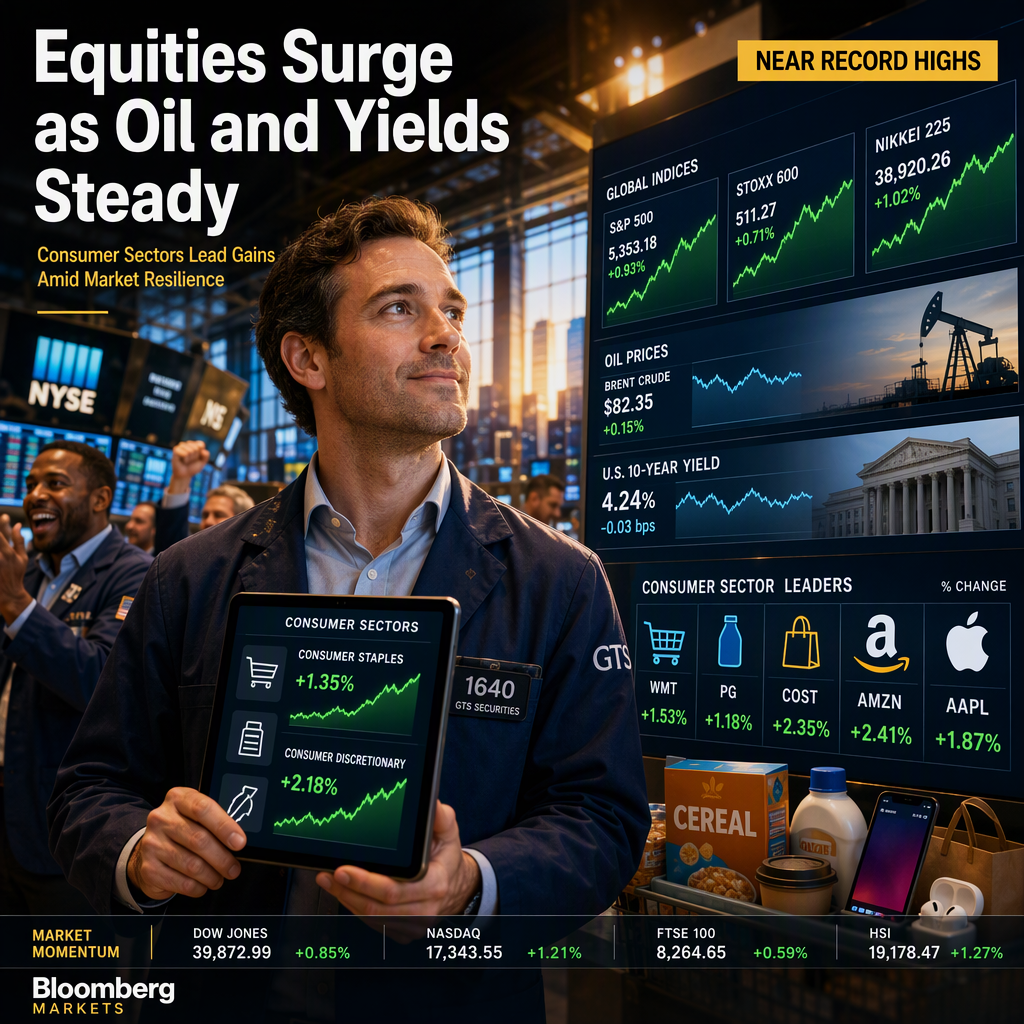
According to Danske Bank, European and US equities ended Friday higher, with many indices approaching all-time highs. This performance was supported by broadly stable yields and oil prices, which have provided a favorable backdrop for stock gains [1]. The Danske Research Team emphasizes that this is not a classic cyclical rally; instead, stabilizing oil prices have particularly benefited consumer staples and consumer discretionary sectors, which had previously struggled due to elevated energy prices following the outbreak of the war in Iran [1].
The report notes that last week demonstrated equities can advance even when yields and oil prices do not necessarily decline, highlighting the resilience of the market in the face of considerable volatility in rates, oil, and energy headlines. Implied bond volatility has gradually eased, further supporting the positive equity environment [1].
Asian equities were described as mixed, with renewed hesitation around AI and technology, while US and European equity futures were higher at the start of the week [1]. Danske Bank suggests that a meaningful decline in oil prices could provide further upside for equities, particularly for energy-sensitive consumer names. However, the bank cautions investors not to assume traditional cyclical leadership, as consumer sectors may continue to be the main beneficiaries of lower energy prices [1].
CONCLUSION
Equities in Europe and the US are advancing, supported by stable oil and yields, with consumer sectors leading gains. The market is not experiencing a classic cyclical rally, and further declines in oil could extend equity gains, especially for consumer-focused stocks. Investors should watch for continued strength in consumer sectors if energy prices ease further.