
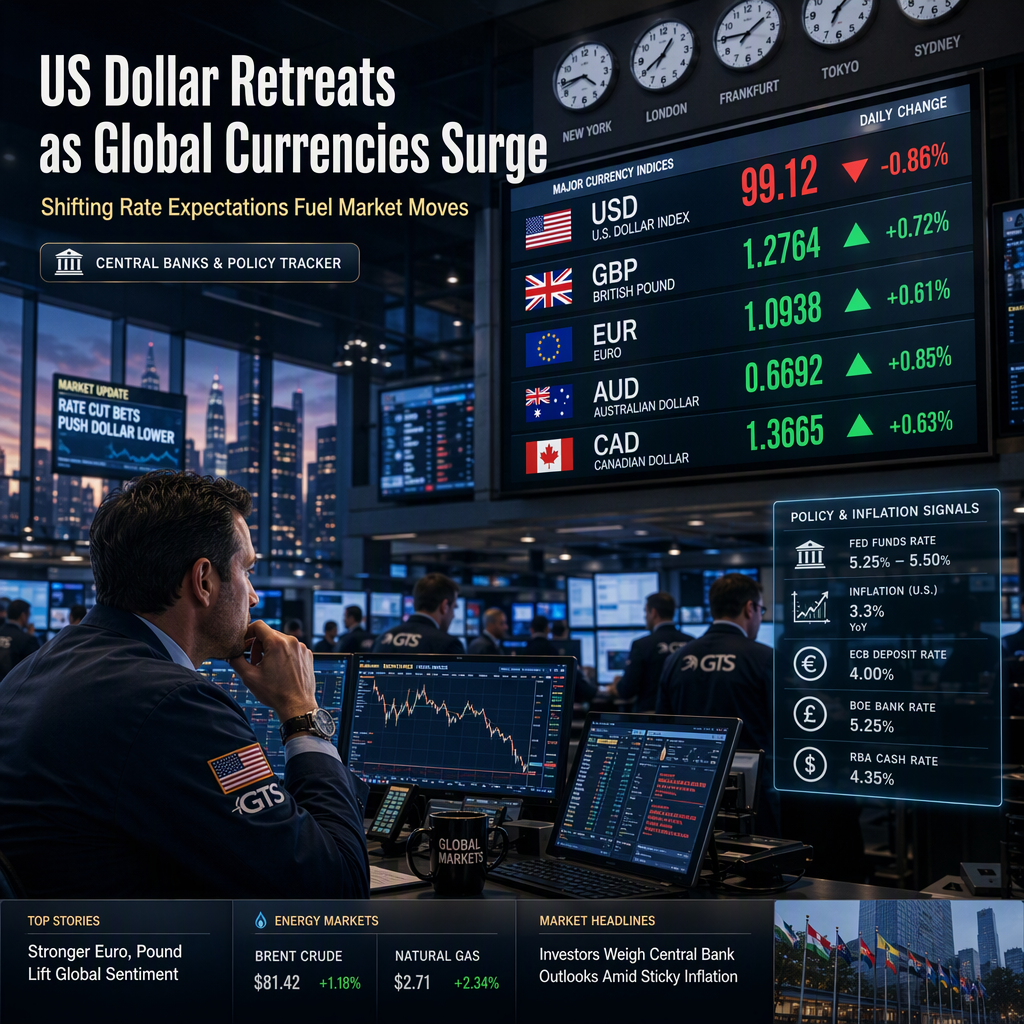
On Tuesday, the US Dollar weakened against several major currencies, with the British Pound, Australian Dollar, Euro, and Canadian Dollar all advancing amid shifting monetary policy expectations and mixed economic data [1][2][3][4]. The Pound Sterling rose by approximately 0.40%, trading at 1.3281, as hawkish comments from Bank of England MPC member Catherine Mann, who warned that inflation is embedded, boosted market bets for a November rate hike. Money markets priced in an 87% chance of a BoE hike, largely due to ongoing Middle East conflict and elevated energy prices [1]. The GBP/USD technical outlook remains bearish in the near term, with resistance at 1.3304 and 1.3428, and support at 1.3159 and 1.3140 [1].
The Australian Dollar gained 0.13%, trading around 0.6980, supported by a modest pullback in the US Dollar and easing US Treasury yields, which fell toward 5.25% before recovering to 5.29%. The US Dollar Index (DXY) retreated to 101.87 after reaching a year-to-date high of 102.53 on Monday [2][3]. Softer US Nonfarm Payrolls and PCE inflation data reduced pressure on the Federal Reserve to raise rates at its October 27-28 meeting, with CME FedWatch indicating a 78% probability of a hold. However, persistent inflation keeps the possibility of a December hike alive, and investors await the FOMC Minutes for further guidance [2][3]. On the Australian side, money markets see only a 20% chance of an RBA rate hike in November, limiting policy support for the AUD [2].
The Euro also found relief from the softer US Dollar, trading up 0.29% at 1.1255. However, concerns over France’s fiscal position and cautious remarks from ECB officials, including Olli Rehn, who noted that inflation has not spread to non-energy prices or wages, kept gains in check. TD Securities commented that the policy backdrop no longer provides incremental support for the Dollar, suggesting the peak in Fed hawkishness has likely passed and limiting further upside for the USD [3].
The Canadian Dollar gained against the US Dollar, with USD/CAD falling 0.15% to 1.4240, despite weaker Oil prices. Oil supply from the Middle East has recovered, with crude shipments at 17.5 million barrels per day, 98% of pre-war levels, and refined products at 3 million barrels per day. The G7’s release of 100 million barrels from reserves and Kuwait’s production recovery to 75% of pre-conflict levels, along with Saudi Arabia lowering prices for Asian buyers, have pressured Oil prices, negatively impacting the CAD [4]. However, US employment data showed private employers added an average of 23.75K jobs per week in the four weeks ending September 19, up from 22.5K previously [1][4]. Brown Brothers Harriman expects Canada’s September labor force survey to show only +5.0k jobs added after a loss of -41.7k in August, with the unemployment rate rising to 6.5%, highlighting weak labor demand and a fragile hiring backdrop. BBH argues that aggressive BoC rate hike pricing leaves CAD vulnerable to dovish repricing [4].
CONCLUSION
The US Dollar's retreat on Tuesday allowed major global currencies to advance, driven by shifting rate expectations and mixed economic signals. While hawkish BoE comments and softer US data influenced market bets, persistent inflation and upcoming central bank meetings remain key for future moves. The overall sentiment is cautiously optimistic for non-USD currencies, but ongoing uncertainties in energy prices and labor data continue to shape the outlook.