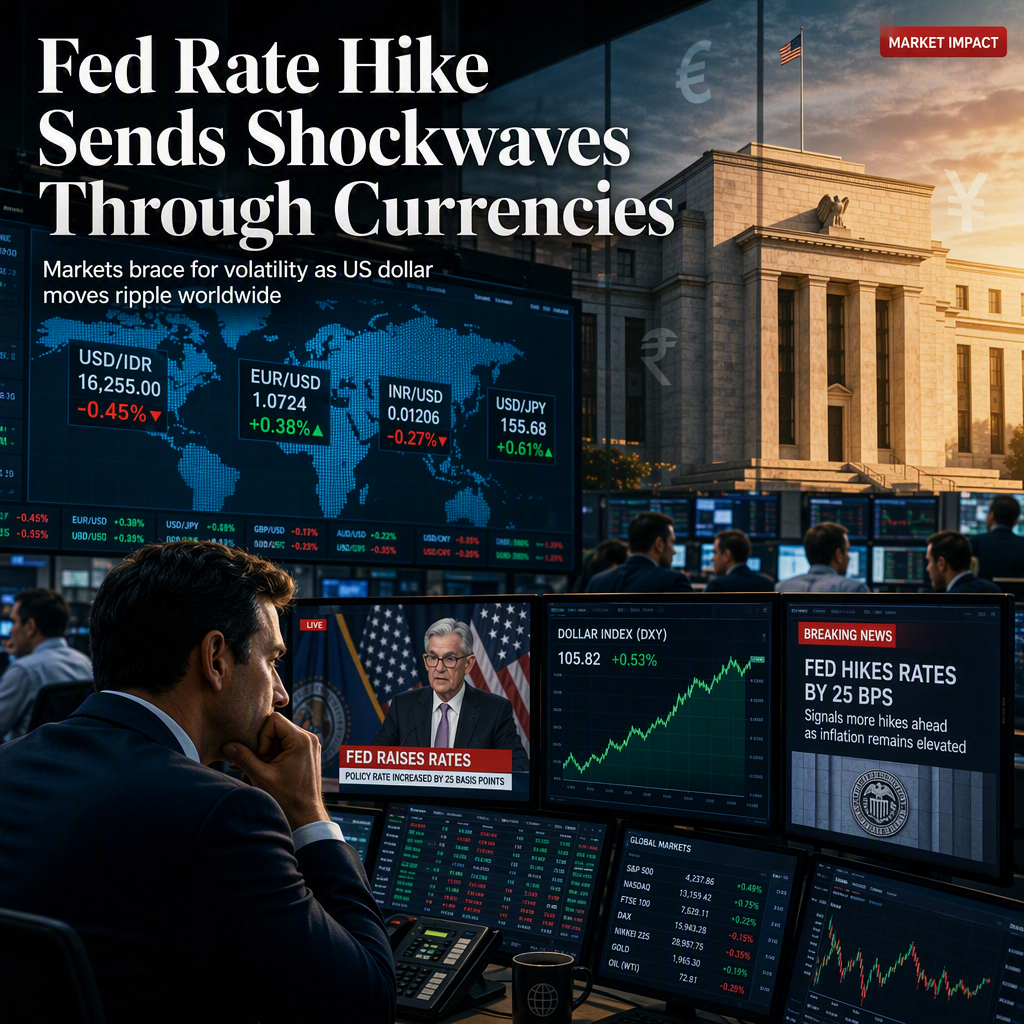
The Federal Reserve is widely expected to raise interest rates by 25 basis points to a range of 3.75%-4.00% at its policy meeting today, breaking a five-meeting streak of holding rates steady. This expectation is supported by sticky US inflation data, with the CME FedWatch tool indicating a 92.4%-92.5% probability of a quarter-point increase, and financial markets pricing in at least one more hike this year, possibly in December, according to ABN Amro and Deutsche Bank strategists [1][2][3]. Investors are closely watching Fed Chair Kevin Warsh's press conference and updated economic projections for further guidance on the policy outlook [2][3][4].
The US Dollar has weakened ahead of the Fed decision, leading to gains for the Indonesian Rupiah (IDR), which halted a four-day losing streak and traded around 17,740 during Asian hours. However, analysts warn that the IDR may face renewed pressure due to domestic economic challenges, such as weak factory activity, fragile consumer sentiment, and slowing retail sales, as well as external risks like rising global crude oil prices and cautious foreign investors. Indonesia also faces policy uncertainty following the abrupt dismissal of Finance Minister Purbaya Yudhi Sadewa, with Deputy Finance Minister Suahasil Nazara now elevated to the top job, marking the third finance minister in less than two years [1].
The Euro (EUR) is trading cautiously at around 1.1545 against the US Dollar, with technical analysis indicating a mildly bearish tone and key support at 1.1500. The EUR/USD pair remains under pressure as investors await the Fed's decision, and strategists at Scotiabank describe the setup as 'neutral/bearish.' ABN Amro analysts frame the expected rate hike as 'inflation insurance,' not the start of a long hiking cycle, and anticipate a single additional hike in December, contingent on inflation dynamics [2].
The Indian Rupee (INR) continues to struggle, trading near a seven-week high of 96.00 against the US Dollar, despite intervention by the Reserve Bank of India (RBI) in spot and NDF markets. US Treasury yields remain elevated, with the 10-year yield near 4.98%, close to its 19-year high of 5.04%. Deutsche Bank notes that markets have priced in 90 basis points of Fed hikes by June 2027, reflecting firm expectations for further tightening. Societe Generale highlights broadening inflation pressures in India, particularly in services, which may prompt the RBI toward a mini hiking cycle [3].
The Japanese Yen (JPY) remains depressed near a one-week low versus the US Dollar, with the USD/JPY pair trading around 155.45-155.50. The immediate market reaction is expected to be limited, as traders have already priced in a 25 basis point rate hike by the Bank of Japan at its upcoming meeting, with a possible follow-up move in December. Elevated US Treasury yields and energy-driven inflation risks continue to support the US Dollar, while technical analysis shows the USD/JPY pair maintaining a bullish intraday bias [4].
CONCLUSION
The Federal Reserve's anticipated 25 basis point rate hike is driving significant volatility across global currency markets, with the US Dollar's movements impacting the Indonesian Rupiah, Euro, Indian Rupee, and Japanese Yen. Market participants are closely monitoring the Fed's policy statement and Chair Warsh's remarks for signals on future rate hikes. The event is seen as having a high market impact, with ongoing inflation concerns and central bank actions shaping currency trends.