
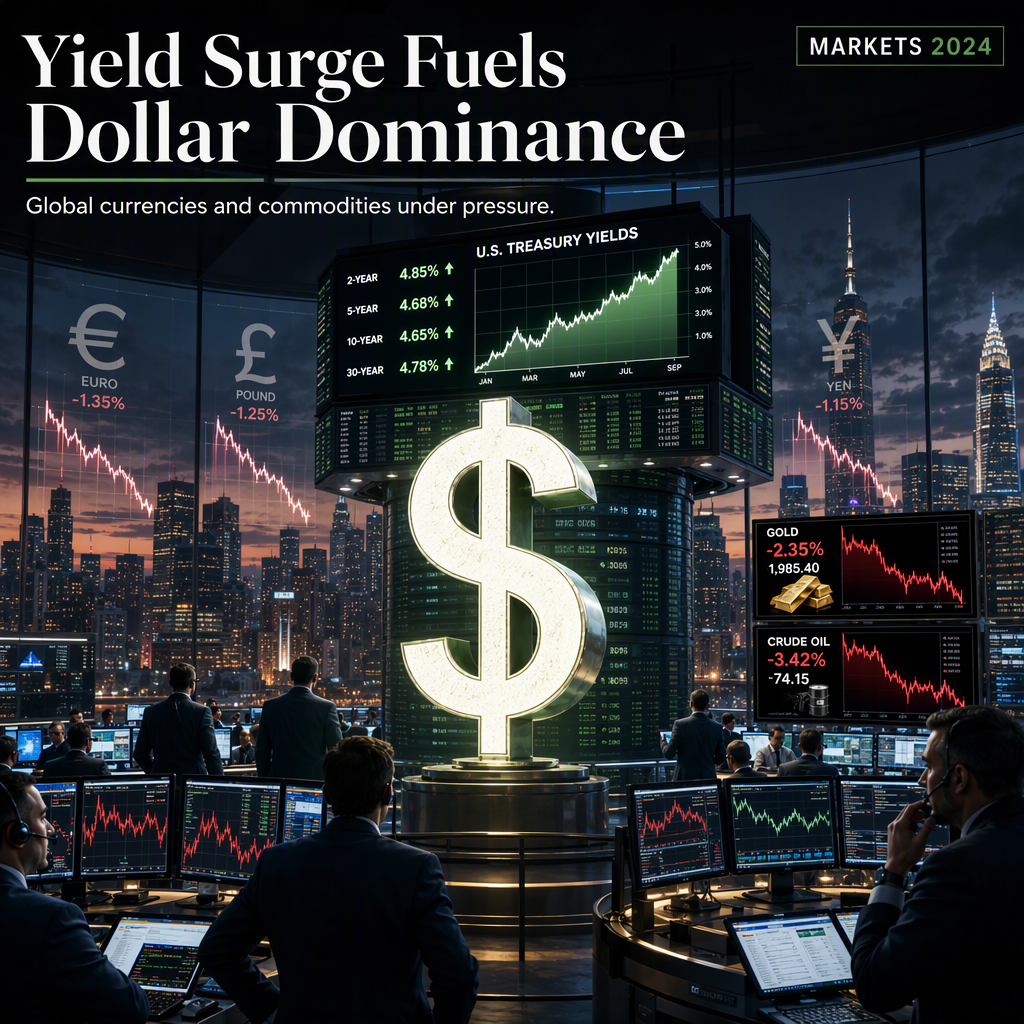
US Treasury yields have surged to multi-decade highs, with the 10-year note reaching above 5.30% and the 30-year note hitting 5.68%—levels not seen in 24 years and since May 2002, respectively [1][5]. This spike in yields is attributed to persistent risk-off sentiment, elevated oil prices above $100, and ongoing geopolitical tensions in the Middle East, which are fueling global inflation concerns [1][5]. Despite softer US Personal Consumption Expenditures (PCE) inflation data for September—showing a 0.3% month-on-month rise and a year-on-year rate falling to 3.4% from 3.7%—the US Dollar has remained robust, supported by strong capital inflows and expectations that higher yields will continue to attract investment [1][3][5][6]. Futures markets have reduced the probability of another Federal Reserve rate hike in October to 37%, down from nearly 70% a week ago [1][5].
The Dollar's strength has weighed heavily on major currencies. The British Pound (GBP/USD) hit three-month lows just below 1.3200, with speculative net shorts on the Pound increasing by more than 40% to their highest level since August, according to Rabobank [1]. The Euro (EUR/USD) dropped below 1.1300 for the first time since May 2025, completing a 2.8% selloff over four weeks, as concerns about France's record-high public debt and gridlock in government savings plans exacerbated market pessimism [5]. Manufacturing PMI data for both the UK and Eurozone showed moderate expansion—UK revised to 51.9 and Eurozone upgraded to 52.9—but failed to offset the negative impact of rising yields and energy prices [1][5].
The Japanese Yen has also weakened, with USD/JPY closing flat at 157.41 after the Ministry of Finance confirmed no FX intervention between August 27 and September 28, following July's record $98.7bn coordinated US-Japan operation [4]. Prime Minister Sanae Takaichi stated that her administration aims to boost Japan's growth potential and market confidence in the yen through investment in crisis management and growth areas, but analysts at OCBC and Societe Generale warn that intervention alone is unlikely to deliver a sustained recovery without domestic policy changes [7]. The dollar traded at 158.37 yen as of Thursday morning, down from a peak above 163 in July but up 7.65% over the past year [7].
Commodities have also been affected. Gold spot retreated from intraday highs of $4,219/oz to close 0.6% lower at $4,157/oz, as elevated real yields capped bullion's upside despite broader macro uncertainty [6]. The Australian Dollar outperformed risky peers but remained flat against the US Dollar at around 0.6945, as a weak trade balance and strong US yields limited gains [2]. The Reserve Bank of Australia raised rates by 25 bps to 4.6%, its fourth hike this year, with Governor Michele Bullock keeping the door open for further tightening [2].
Looking forward, analysts at ING suggest the Dollar will remain strong in October barring a breakthrough in US-Iran negotiations or a surprise in US data, and warn of further upside if European debt sell-offs intensify [5]. Societe Generale's Kit Juckes notes that higher US yields and dollar-friendly policies will keep supporting the Dollar until US growth begins to suffer, which is unlikely to happen before Europe does in the current global energy crisis [3].
CONCLUSION
The surge in US Treasury yields has reinforced the US Dollar's dominance, pressuring global currencies and commodities. Despite softer US inflation data, market sentiment remains risk-off, with analysts expecting continued Dollar strength unless major geopolitical or economic surprises occur. The outlook for other currencies and commodities remains subdued as elevated yields and energy prices persist.