
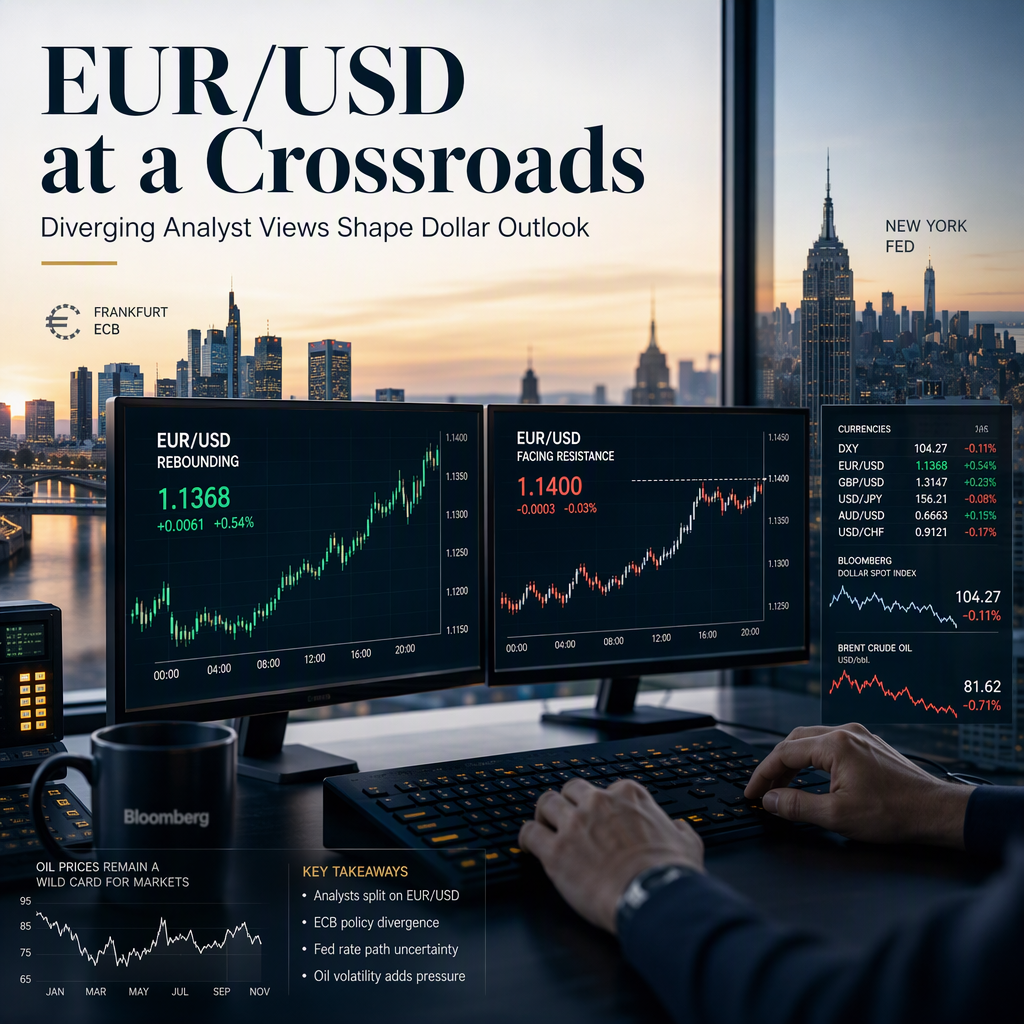
The recent movement in EUR/USD has drawn attention from major financial institutions, with Societe Generale and Deutsche Bank offering differing perspectives on the currency pair's outlook. Societe Generale’s Kit Juckes highlights a softer Dollar environment as oil and bond yields decline and equities strengthen, attributing some of the moves to month-end flows. However, Juckes cautions that unless EUR/USD can reclaim at least 1.14, the rebound will likely be interpreted as another opportunity to sell the euro, especially given negative sentiment from softer European data and interest-rate differentials that continue to favor the Dollar. Markets are currently pricing in three ECB rate hikes before mid-next year, but Juckes questions whether Eurozone growth is sufficient to justify this, suggesting the market may be overreacting to a temporary inflation shock linked to the ongoing energy crisis [1].
In contrast, Deutsche Bank maintains a more constructive view on EUR/USD, arguing that the pair is likely to remain within its 1.13–1.20 yearly range rather than break lower. The bank cites resilient global growth, peak USD yield support, and an energy shock that appears increasingly priced in. Deutsche Bank’s FX Blueprint maintains a 1.17 EUR/USD forecast for year-end, emphasizing that further Fed-driven Dollar upside is limited and that now is not the time to chase EUR/USD lower. The bank also notes that terminal Fed pricing looks complete, with New York Fed President Williams pushing back on consecutive rate hikes, and that any additional US rate rises are more likely to come from higher term premiums, which historically do not support an appreciating USD [4].
Elsewhere in the FX market, Societe Generale’s FX team reports that USD/JPY traded between 156.38 and 157.52 overnight, with the pair mildly offered following dovish comments from New York Fed President John Williams and fiscal half-end repatriation flows. Key technical levels are identified at 155 (support) and 158.20 (resistance), with a notable option strike at 157.00 worth $1.4 billion [2].
Emerging market currencies have also been impacted, with Societe Generale’s Kenneth Broux noting a sharp unwind in carry trades, particularly in the Mexican Peso, which is down 6% on spot and 5.2% on a total return basis for the month. The outlook for further adjustment in Q4 will depend on US Treasury yields, oil prices, and the implications of US mid-term election results for fiscal policy. The South African Rand is also at a critical juncture, trading near its 200-day moving average at 16.38 after rebounding from sub-16.00 levels, despite a recent 25bp rate hike by the SARB. Broux warns that further sell-offs in US long bonds and a recovery in the Yen could increase pressure on carry trades and exacerbate corrections in currencies like MXN and ZAR [3].
CONCLUSION
The EUR/USD remains at a pivotal level, with Societe Generale expressing caution about the Euro's ability to sustain a rebound and Deutsche Bank maintaining a more optimistic, range-bound outlook. Broader FX markets are experiencing volatility, particularly in emerging market currencies, as global yield dynamics and central bank signals continue to drive sentiment. Market participants are advised to monitor key technical levels and macroeconomic developments closely.