
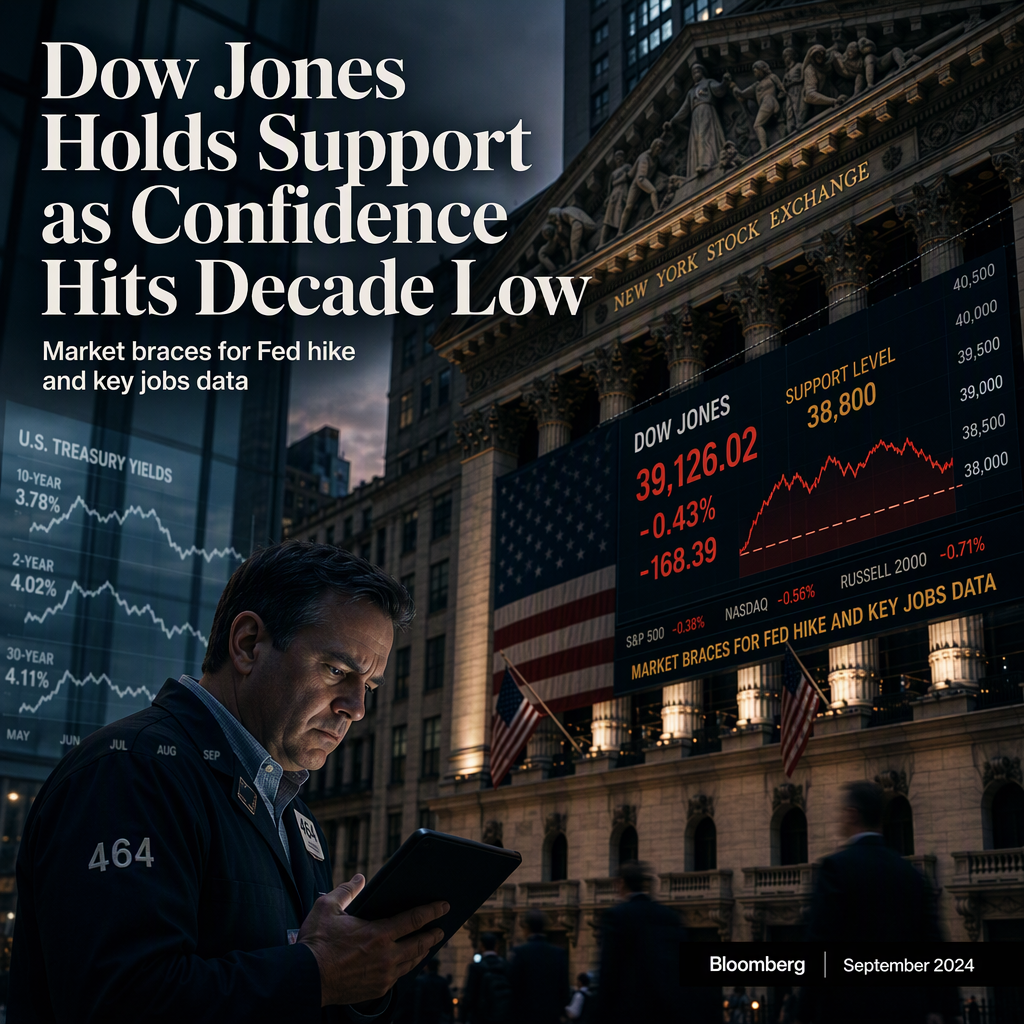
The Dow Jones Industrial Average (DJIA) retested its September floor near 51,100 after the worst US consumer confidence reading since 2014, but the index managed to hold this support level for the third time this month [1]. The Conference Board's consumer confidence index dropped sharply to 81.9 from 88.6, missing the forecast of around 89. Survey respondents indicated expectations for weaker business conditions and a softer job market over the next six months, with their view of current business conditions turning negative for the first time since September 2024 [1]. Job openings also disappointed, coming in at 7.08 million in August versus a 7.23 million forecast [1].
Despite these soft economic indicators, Treasury yields climbed, with the 10-year yield reaching its highest level since 2007 and the 30-year at its highest since 2002. The Dow has fallen about 3.5% in September with one session left, threatening to end a five-month winning streak, while the S&P 500 is down 0.2% for the month [1]. The Dow is also down nearly 2% for the third quarter [1]. The Federal Reserve raised rates on September 16 for the first time since 2023, and futures markets are still pricing in another quarter-point hike on October 28 [1].
Looking ahead, several key data releases are expected, including August personal income and spending, the core PCE price index (forecast up 0.3% MoM), ADP private payrolls (forecast at 70K), and the Chicago PMI (forecast at 51.2) [1]. Weekly jobless claims are forecast at 200K, and the ISM factory survey headline index is expected at 55. Nike (NKE), a Dow component, will report earnings after the close [1]. September payrolls, due Friday, are forecast at 90K after 162K in August, with the unemployment rate expected to remain at 4.1% [1].
The article notes that firm spending and payroll numbers would give the Fed room to hike rates again in October, while a weaker jobs report could help pull Treasury yields off their highs. The Dow's performance remains closely tied to movements in yields, and technical resistance is noted at the 51,800 and 52,000 levels [1].
CONCLUSION
The Dow Jones Industrial Average is under pressure from weak consumer confidence and job data, but has so far held a key support level. Rising Treasury yields and the prospect of further Fed rate hikes are weighing on the market, with upcoming economic data and earnings reports likely to influence the next move. Market sentiment remains cautious as investors await signals that could shift the current negative trend.