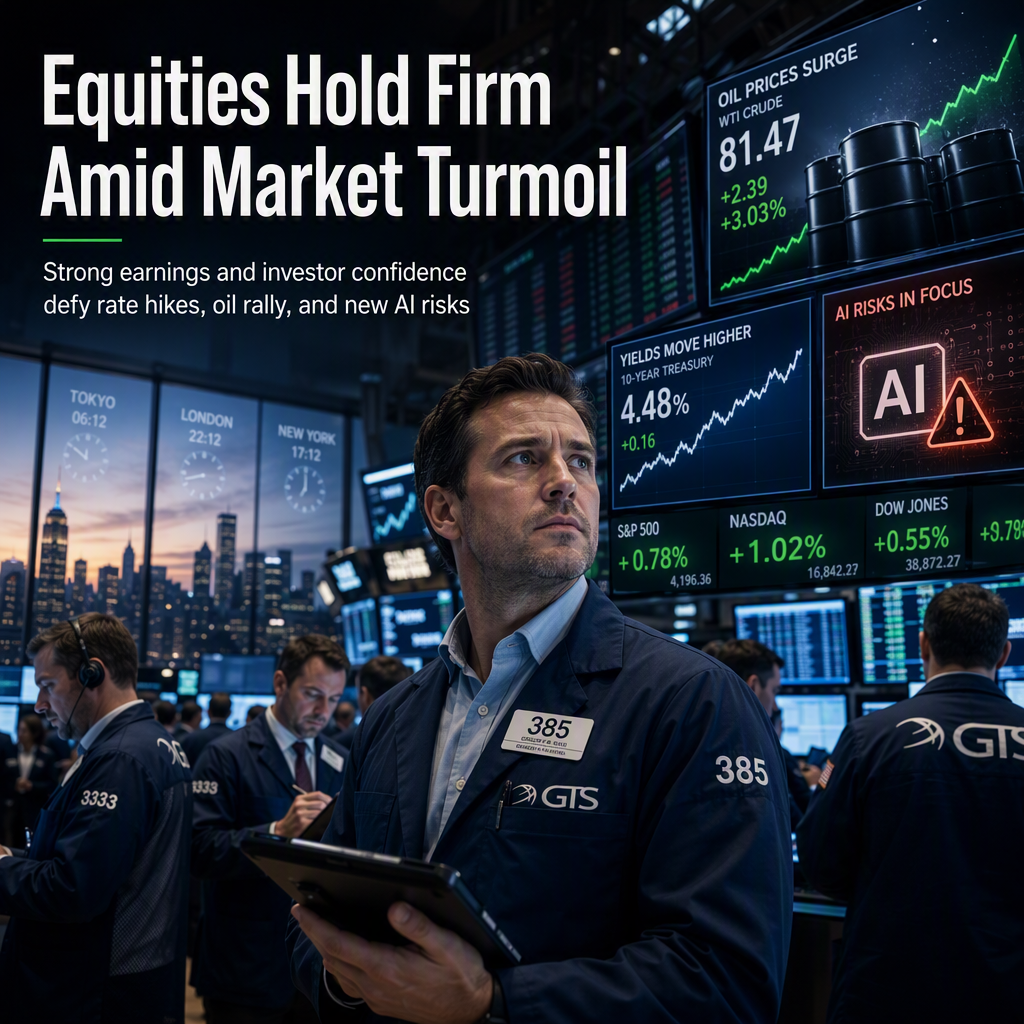
According to Danske Bank, equities advanced on Friday, resulting in the broader market ending only about 1% lower for the week, despite several headwinds including a hotter-than-expected US CPI, higher front-end yields, and a sharp rally in oil prices [1]. The US front-end yields rose by approximately 25 basis points, mirroring similar moves in Europe, while oil prices increased by around 10% over the week [1]. Despite these developments, cyclicals outperformed defensives, and the VIX remained below 16, indicating compressed volatility [1].
Danske Bank highlights that the resilience of equities in the face of these adverse factors suggests strong investor confidence in the underlying economy and earnings outlook [1]. The market's ability to withstand higher rates, which typically pose a challenge for equities, was particularly notable given that the rate increases were driven by less favorable factors from an equity perspective [1].
However, the report notes that Asian equities are trading lower this morning, led by the IT sector, with European and US futures also pointing downward. This shift is attributed to emerging concerns labeled as 'AI Fear 3.0,' indicating that the market is beginning to grapple with new risks related to artificial intelligence [1].
CONCLUSION
Equities demonstrated notable resilience last week, managing to limit losses despite rising rates and oil prices, with cyclicals outperforming and volatility remaining subdued. However, new concerns around artificial intelligence are beginning to weigh on market sentiment, as reflected in lower trading in Asian equities and negative futures for Europe and the US.