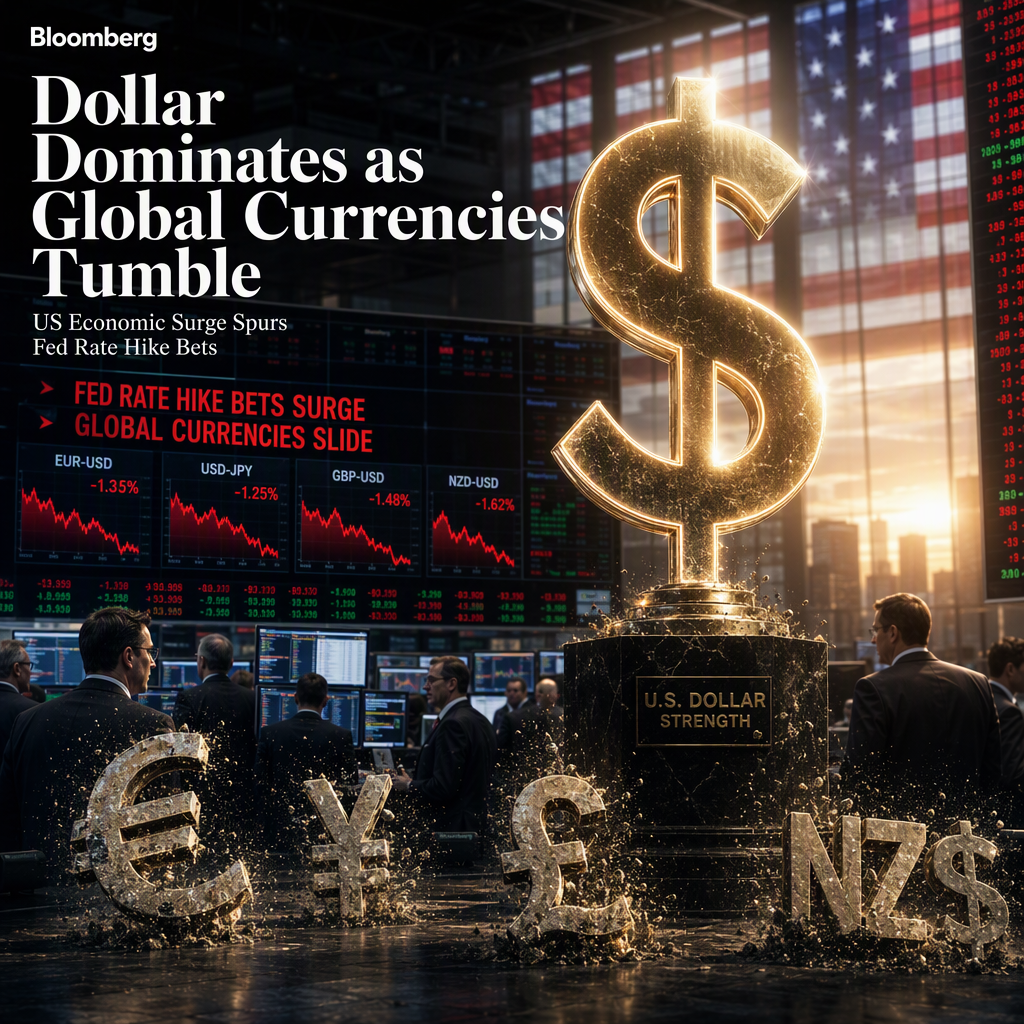
A series of strong US business surveys has triggered a broad selloff in major global currencies, with the New Zealand Dollar, Japanese Yen, Euro, and British Pound all weakening against the US Dollar. The New Zealand Dollar (NZD/USD) slid toward the bottom of its trading range, falling just under 0.5700, its lowest since early July, as two-year US government bond yields climbed to about 4.9% following robust US business data. The Reserve Bank of New Zealand (RBNZ) has raised its Official Cash Rate twice since July 8, reaching 2.75% on September 2, but its forecast points to no change at the October 28 meeting and a potential rise to 3.00% in December. RBNZ Governor Breman warned that near-term inflation could exceed forecasts if crude oil prices remain high, but this was characterized as a caution rather than a commitment to further hikes. Analysts also noted the importance of China, New Zealand's largest export market, with President Xi scheduled to meet President Trump at the White House, though expectations for trade deals are low [1].
The Japanese Yen (USD/JPY) also weakened, trading above 158.00 and on track for its first daily close above its 200-day average since September 2. Japan's Finance Ministry intervened heavily in currency markets, spending ¥15.4 trillion between July 30 and August 26, but the Yen continued to lose ground. The Bank of Japan (BoJ) raised its rate to 1.25% on September 18, the highest since 1995, but with the US Federal Reserve's rate at 3.75-4.00%, the yield differential continues to favor the Dollar. Fed Governor Barr argued for more rate increases, reinforcing the Dollar's strength. Japanese markets, closed for national holidays, are set to reopen with the Yen at weaker levels than before the BoJ's rate hike [2].
The Euro (EUR/USD) extended its decline, falling just under 1.1400 despite the eurozone's flash PMI composite reading of 53.1, which beat the 51.5 forecast and marked the strongest result since April 2023. The European Central Bank (ECB) raised its deposit rate to 2.50% on September 10, its second increase this year, but traders focused on the even stronger US survey results and increased bets on another Fed hike at the October 28 meeting. ECB policymakers Schnabel and Lane are scheduled to speak, with the next ECB decision on October 29, one day after the Fed's. Political uncertainty in Germany following state election losses also weighed on the Euro [3].
The British Pound (GBP/USD) sold off sharply, trading just under 1.3250, its lowest since early July, after US services PMI came in at 58.7 versus a 56 forecast, while UK services missed expectations at 51.7 versus 52. The Bank of England (BoE) held its rate at 3.75% on September 17 in a 6-3 vote, with some members advocating for a hike to 4%. Upcoming BoE speakers all voted to hold rates, suggesting little immediate prospect of a November hike. The UK's final major data release for the week is GfK consumer confidence, forecast to fall further, while the US has several key releases remaining, likely to keep the focus on US economic strength [4].
Across all four currencies, the dominant theme is the outperformance of the US economy and the rising likelihood of further Fed rate hikes, which has driven investors toward the Dollar and away from other major currencies. Technical indicators in all pairs suggest oversold conditions, but the prevailing bias remains bearish for non-USD currencies unless key resistance levels are reclaimed [1][2][3][4].
CONCLUSION
Stronger-than-expected US economic data and rising US yields have led to a broad selloff in major currencies against the Dollar, as markets increasingly price in further Fed rate hikes. Central banks in New Zealand, Japan, the eurozone, and the UK have all taken recent action, but the yield differential and economic momentum continue to favor the US. Unless upcoming data or central bank commentary shifts expectations, the Dollar is likely to remain dominant in the near term.