
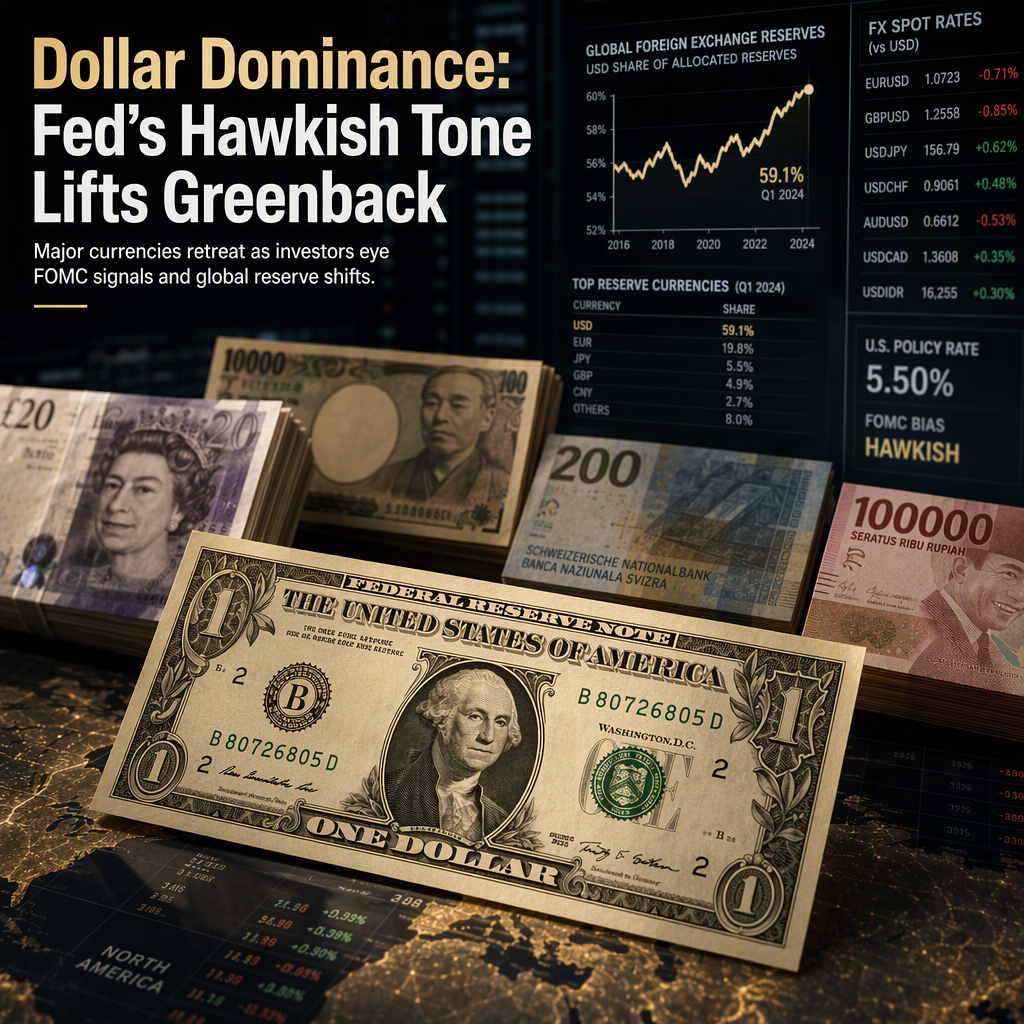
The US Dollar (USD) exhibited broad-based strength against major currencies on Wednesday, with notable moves in USD/IDR, GBP/USD, USD/JPY, and USD/CHF pairs, as investors digested global reserve data and awaited the release of the Federal Open Market Committee (FOMC) minutes later in the day [1][2][3][4]. The Indonesian Rupiah (IDR) remained subdued, trading around 17,900 against the USD, following a slight dip in Indonesia's foreign reserves to USD 146.3 billion in September from USD 146.5 billion in August. Despite the decline, reserves remain robust, covering 5.3 months of imports and 5.2 months of imports plus government external debt servicing, well above the international adequacy benchmark [1]. Bank Indonesia affirmed that the reserve level is sufficient to support external sector resilience and macroeconomic stability [1].
The British Pound (GBP) traded 0.18% lower at 1.3248 against the USD, pressured by the Greenback's outperformance ahead of the FOMC minutes. The US Dollar Index (DXY) rose 0.22% to 102.07, reflecting investor anticipation of Fed policy signals. The CME FedWatch tool indicated an 81% probability that the Fed will keep rates unchanged at its upcoming meeting, with recent soft US labor data and Fed signals reducing expectations for further hikes [2]. Fed’s Williams delivered a moderately hawkish message, emphasizing data dependence and the need to return inflation to 2%, with projections for inflation reaching target only in 2028 and unemployment at 4% over 2027, suggesting a prolonged restrictive policy stance [2].
In the USD/JPY pair, the Dollar touched a one-and-a-half-week high near 158.50, buoyed by firmer US bond yields and persistent geopolitical uncertainties. Despite moderating US inflation and labor market data, traders are pricing in an 85% chance of a Fed rate hike by year-end. Expansionary fiscal policies in Japan and a cautious Bank of Japan (BoJ) weighed on the Yen, while technical indicators showed bullish momentum but warned of vulnerability to selling pressure [3]. The Japanese Yen was strongest against the New Zealand Dollar, but overall, the USD gained 0.26% against the JPY on the day [3].
The Swiss Franc (CHF) declined, with USD/CHF trading around 0.8330, as investors awaited Switzerland's foreign currency reserves data. The unemployment rate remained steady at 3.1% for the fifth consecutive month. Despite haven demand driven by France's sovereign debt concerns, the USD/CHF pair appreciated on the back of higher crude oil prices and Middle East supply risks, which kept inflationary concerns and rate-hike expectations in focus. The CME FedWatch tool reflected a 20% probability of a Fed rate hike at the October meeting, with Fed’s Schmid emphasizing AI-driven price pressures and the need for a prolonged period of elevated policy rates. The FXS FedSentiment Index rose to 137.91, reinforcing hawkish Fed expectations [4].
Across all pairs, technical analysis highlighted resistance and support levels, with USD/IDR holding above its 50-day EMA, GBP/USD extending its retreat below the 20-period EMA, USD/JPY capped below the 100-day SMA, and USD/CHF benefiting from a hawkish Fed backdrop [1][2][3][4].
CONCLUSION
The US Dollar's strength was reinforced by hawkish signals from Fed officials and robust reserve data from Indonesia and Switzerland, despite softer US labor market readings. Market participants remain focused on the Fed's policy outlook, with technical and sentiment indicators suggesting continued support for the Dollar against major currencies. The upcoming FOMC minutes and global reserve trends are likely to shape near-term currency movements.